Lost Pension Pots 2026: How To Find And Claim What Is Yours
[…]

Broker reviews
Choose a UK investing platform
 eToro
 Plus500
 Interactive Brokers
 J.P. Morgan
 Vanguard UK
 Trading 212
 AJ Bell
 Trading.com
 Lightyear
 Webull UK
 XTB UK
 Robinhood UK
 Hargreaves Lansdown
 Interactive Investor
 InvestEngine
Every review covers fees, account types, safety and FCA regulation, and is updated as providers change their pricing.
A side by side comparison of two commission-free investing apps with low cost ISAs, covering fees, cash interest, account types, investment choice and who each one actually suits.
By Dimitar Kanazirski, Editor-in-chief
Published: | Fact-checked by: David Katzarov | Last updated:
Zero commission | 0.15% FX | ISA, Cash ISA, SIPP
Capital at risk.
Zero commission | Interest on cash | Flexible ISA
Capital at risk.
Zero commission | 0.15% FX | ISA, Cash ISA, SIPP
Zero commission | Interest on cash | Flexible ISA
Quick verdict
Trading 212 is cheaper to run for most ISA investors who buy overseas shares. Both charge no commission and no ISA platform fee, but Trading 212's FX fee is 0.15% against XTB's 0.5%, and it adds a SIPP. Choose XTB if you keep more cash uninvested, want automated ETF Investment Plans, or value a dedicated account manager.
Trading 212 is a London based, FCA authorised platform built around commission-free investing in stocks and ETFs. UK clients contract with Trading 212 UK Ltd, and there is no platform, custody or inactivity fee. The accounts cover general investing, a Stocks and Shares ISA, a Cash ISA, a SIPP launched in 2026 and a separate CFD account. The one recurring cost most people meet is a 0.15% FX fee when a purchase is priced in a currency other than sterling.
It suits cost conscious investors who want stocks and ETFs inside a tax wrapper, starting from £1, with Pies and AutoInvest to automate regular investing. It does not offer mutual funds, unit trusts, OEICs or direct bond dealing. Our full Trading 212 review covers the platform in more depth.
XTB is a broker founded in Poland in 2002 and listed on the Warsaw Stock Exchange. UK clients are served by XTB Limited, which is authorised and regulated by the Financial Conduct Authority. It offers commission-free shares and ETFs up to €100,000 of monthly turnover, a free and flexible Stocks and Shares ISA, a flexible Cash ISA, and interest on uninvested cash, quoted at 4.00% on GBP on XTB’s UK website in October 2026. A 0.5% fee applies when you buy assets priced in another currency.
Its Investment Plans automate contributions into a portfolio built from around 500 ETFs, from £15, and fractional shares start at £10. XTB also offers CFDs for experienced traders. Whether you search Trading 212 vs XTB or XTB vs Trading 212, the decision for most ISA investors comes down to currency costs, cash interest and whether you need a pension. Our full XTB review goes through each feature.
| Criteria | Trading 212 | XTB |
|---|---|---|
| Overall rating | ★★★★★★★★★★4.5 / 5 | ★★★★★★★★★★4.4 / 5 |
| Best for | Low cost shares and ETFs, overseas holdings | Cash-heavy ISA investors and regular ETF plans |
| Regulator | FCA (Trading 212 UK Ltd, FRN 609146) | FCA (XTB Limited, FRN 522157) |
| Dealing commission | £0 on shares and ETFs | £0 up to €100,000 monthly turnover, then 0.2% (minimum £10) |
| Platform or custody fee | £0 | £0 below €250,000 |
| Currency conversion fee | 0.15% | 0.5% |
| Interest on uninvested cash | 3.8% AER on GBP (5 August 2026) | 4.00% on GBP (October 2026) |
| Account types | Invest, Stocks and Shares ISA, Cash ISA, SIPP, CFD | General account, Stocks and Shares ISA, Cash ISA, CFD |
| SIPP | Yes, no drawdown yet | No |
| Cash ISA | Yes, 3.6% AER variable (5 August 2026) | Yes, 4% AER variable (from 1 May 2026) |
| Minimum investment | £1 | No minimum deposit; fractional shares from £10 |
| Funds and bonds | No | No |
| Automated investing | Pies and AutoInvest | Investment Plans from £15 |
| Inactivity fee | None | £10 a month on idle general accounts; never on the ISA |
| Withdrawal fee | None | £5 on withdrawals under £50 |
| FSCS protection | £85,000 investments; £120,000 cash per bank | £85,000 investments; £120,000 Cash ISA |
| Customer support | 24/7 in-app chat, email, help centre | 24/5 chat and phone, dedicated account manager |
| Demo account | Yes | Yes, £100,000 in virtual funds |
Fees and product details checked August to October 2026, taken from our Trading 212 and XTB reviews and XTB's UK website. Always confirm current terms on the provider’s own site.
Trading 212
Trading 212 charges no commission on stock and ETF dealing and no platform, custody or inactivity fee, across the Invest account, the Stocks and Shares ISA and the SIPP. Portfolio transfers in and out are free, and there is no withdrawal fee. For a sterling denominated ETF held for the long term, the platform side of the cost is zero, although the fund’s own ongoing charge still applies.
XTB
XTB charges no commission on shares and ETFs while your monthly turnover stays under €100,000; above that, 0.2% applies to the excess, with a £10 minimum. There are no platform or custody fees on accounts below €250,000, after which a 0.02% annual custody charge applies. For someone investing a few hundred pounds a month, dealing and platform costs are effectively zero.
Trading 212
The cost most investors will meet is the 0.15% FX fee on in-app currency conversion, charged when you buy anything not priced in sterling. On a £10,000 purchase of US shares that is £15. You can avoid it by sticking to sterling denominated ETFs, and spending with the 212 Card carries no FX fee at all.
XTB
XTB charges 0.5% when you buy assets priced in a currency other than sterling, such as US shares. On a £10,000 purchase that is £50, against £15 at Trading 212, and the charge applies again when you sell. XTB’s USD and EUR denominated accounts let regular overseas investors avoid repeated conversions.
Trading 212
Card and e-wallet deposits are free for the first £2,000, after which a 0.7% fee applies to further top-ups by those methods, so bank transfer is the cheaper route for larger sums. The CFD account is priced differently, through spreads and overnight fees. You can compare running costs across UK platforms with our broker fees calculator.
XTB
Withdrawals under £50 cost £5, while larger withdrawals and bank transfer deposits are free. A £10 monthly inactivity fee applies to the general account after 12 months without a trade and 90 days without a deposit, but never to the ISA. UK share purchases carry 0.5% stamp duty, a government tax rather than an XTB fee.
Trading 212
Trading 212 offers an Invest account, a Stocks and Shares ISA, a flexible Cash ISA, a SIPP and a separate CFD account, and money can be moved between the wrappers. The SIPP received FCA authorisation in February 2026 and is operated by Platform One, with no platform fee and no dealing charge. There is no drawdown yet, so taking a retirement income would currently mean transferring the pension out.
XTB
XTB offers a general investment account, a free Stocks and Shares ISA and a Cash ISA paying 4% AER variable from 1 May 2026, with FSCS deposit cover up to £120,000. Both ISAs are flexible, so money withdrawn and replaced in the same tax year does not use up more of your allowance. The Stocks and Shares ISA can currently only be opened in the mobile app. There is no SIPP, no Lifetime ISA and no Junior ISA, so Trading 212 is the only one of the two that can hold your pension as well.
Trading 212
You can start with £1 in the Invest account, either ISA or the SIPP when funding by bank transfer, Apple Pay, Google Pay or a linked UK bank account. Card and e-wallet deposits carry a £10 minimum, as does the CFD account. Fractional shares mean even a small deposit can be spread across several holdings.
XTB
There is no minimum deposit. Fractional shares start from £10, and Investment Plans accept automated contributions from £15. A demo account with £100,000 in virtual funds lets you try the platform first.
Trading 212
Trading 212 is app first, and it shows. Search, order entry and portfolio views are clean and quick, and the learning curve for a first time investor is short. The web platform mirrors the app closely. The trade off is that research tools are thin, with no in depth screeners or professional grade analysis.

XTB
XTB’s platform comes from a trading background, with its learning material and market tools built in. The catch for beginners is that real shares and their CFD versions appear side by side in search results, so you need to choose the stock version rather than the leveraged CFD when placing an order.
Trading 212
The mobile app is how most customers use Trading 212. It handles fractional orders, Pies and recurring investments natively, and 24/5 trading on popular US stocks and ETFs runs from Sunday 22:00 to Friday 21:00 UK time.
XTB
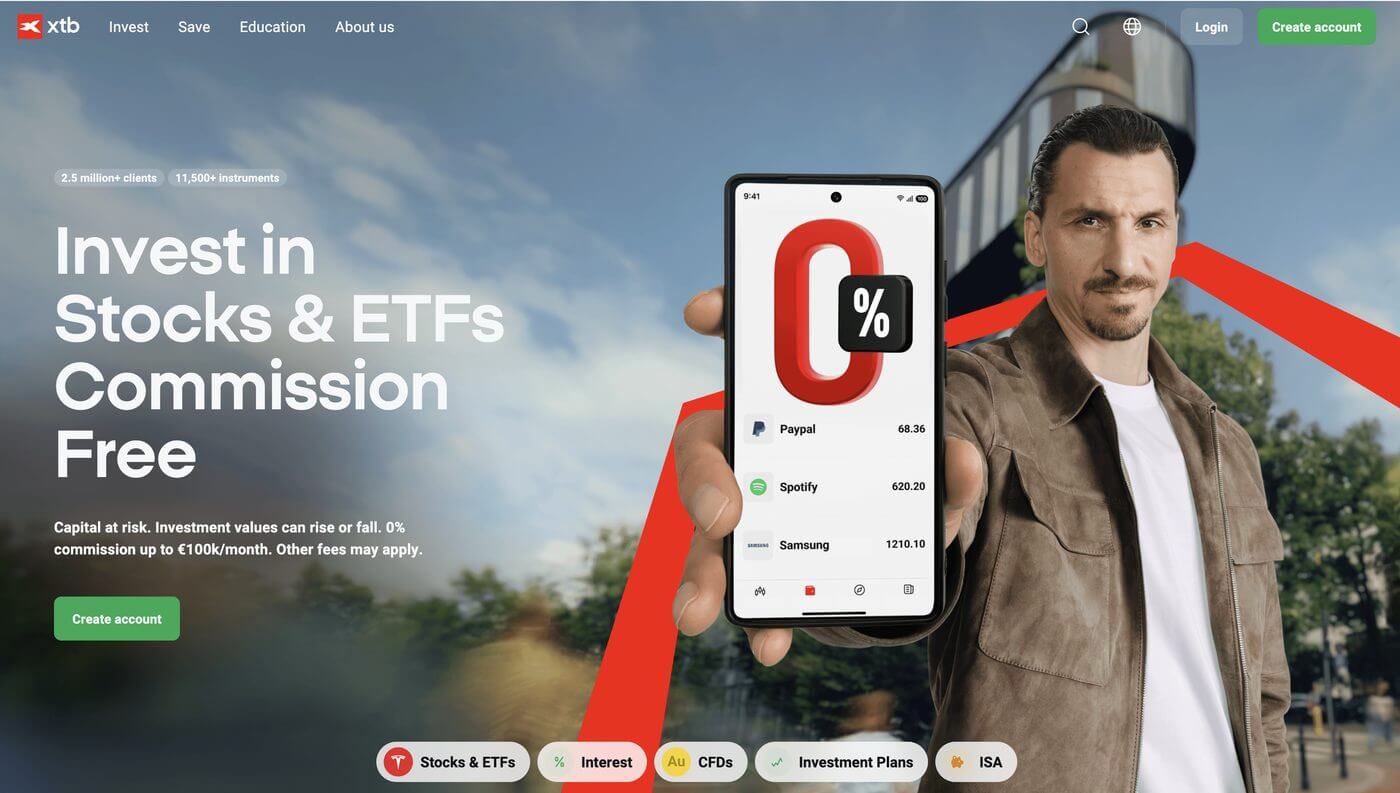
The mobile app is where the XTB ISA lives: it can currently only be opened there, under Portfolio. Investment Plans can also be set up and managed from the app, so a monthly ETF plan can be run entirely from your phone.
Trading 212
Pies let you set target weightings across several holdings, and AutoInvest funds them on a recurring schedule, with rebalancing back to your chosen weights. For a beginner assembling a simple global portfolio, this is one of the most useful features on either platform.
XTB
Investment Plans are XTB’s equivalent of Pies: you build a portfolio from around 500 ETFs, set your weightings and automate contributions from £15, with up to 10 plans at once and no fee. It is a practical middle ground between choosing every holding yourself and paying a robo-adviser’s management fee.
Trading 212
Thousands of stocks and ETFs across exchanges including the London Stock Exchange, NYSE, NASDAQ, Xetra and Euronext, with fractional shares from £1. The same range is available in the Invest account, the ISA and the SIPP.
XTB
Over 6,900 real stocks and 2,200+ ETFs across 16 markets, including the London Stock Exchange, NYSE and Deutsche Börse, with fractional investing from £10. Check that the specific shares or ETFs you want are available in the ISA before you transfer.
Trading 212
None. Trading 212 offers no mutual funds, unit trusts or OEICs and no direct bond dealing. For many investors an ETF does the same job, but if your plan calls for a specific fund, Trading 212 cannot hold it.
XTB
None. Like Trading 212, XTB offers no mutual funds, bonds or investment trusts. If your plan needs those inside an ISA, neither platform is the right home for it.
Trading 212
A separate CFD account for leveraged trading, where 77% of retail investor accounts lose money with this provider. There is no direct crypto for UK clients, only crypto ETNs, and new crypto ETN purchases are not permitted inside a Stocks and Shares ISA from 6 April 2026. Share lending is available on the Invest account on an opt-in basis.
XTB
A CFD account for experienced traders, covering forex, indices, commodities, shares and ETFs, where 74% of retail investor accounts lose money with this provider. XTB also pays interest on uninvested cash and runs a Trading Academy of more than 200 lessons.
Trading 212
Trading 212 UK Ltd is authorised and regulated by the Financial Conduct Authority under firm reference number 609146. Investments are held in segregated accounts with Interactive Brokers and Bank of New York Mellon under the FCA’s client asset rules, with an annual external review of its asset protection processes. In early 2026 the Financial Times reported that Trading 212 had offered crypto ETNs before holding the relevant permission, which it then obtained.
XTB
XTB Limited is authorised and regulated by the Financial Conduct Authority under firm reference number 522157. Client money is held in segregated bank accounts, separate from company funds. The wider XTB Group is listed on the Warsaw Stock Exchange and publishes audited accounts.
Trading 212
Uninvested cash held with partner banks is covered by the FSCS up to £120,000 per person, per bank. Investments are covered separately up to £85,000. Cash placed in qualifying money market funds to earn interest counts as an investment, so the deposit limit does not apply to that portion.
XTB
Eligible clients are covered by the Financial Services Compensation Scheme for investment claims up to £85,000 if XTB fails. XTB’s ISA is its own product, held with XTB Limited. As with any platform, the scheme protects you against the firm failing, not against your investments falling in value.
Trading 212
Chat support runs 24/7 in the mobile and web apps, starting with an AI chatbot and handing over to a human on request. There is also email, a help centre and an active community forum.
XTB
Live chat and phone support run around the clock on weekdays, alongside email. Every client is also assigned a dedicated account manager, reachable by email and WhatsApp, although they cannot give investment advice.
Trading 212
Support is generally well rated, but capacity has been stretched during periods of high market volatility when contact volumes spike. The help centre covers most routine questions on fees, transfers and ISA rules.
XTB
Email replies typically arrive within one business day, and in our research in-app chat queries were answered quickly. New clients are usually contacted by their account manager with an offer of a platform walkthrough, which you can decline.
Trading 212
Trading 212 runs a learning hub alongside its help centre, covering platform mechanics, ISA rules and general investing concepts. The material is clear and aimed at getting you comfortable with the product.
XTB
XTB’s Trading Academy runs to more than 200 lessons and is free to use, making education one of the platform’s clear strengths.
Trading 212
A free demo account with virtual funds lets you practise before committing real money, and the community forum is often the fastest route to an answer on how a feature works.
XTB
A free demo account with £100,000 in virtual funds lets you learn the platform before committing real money, including how to tell a share from its CFD version.
Trading 212
Best for someone who learns by doing and wants to start small. Our guide to dollar cost averaging pairs well with Pies and AutoInvest.
XTB
Best for someone who wants structured lessons and a named person to ask, thanks to the Trading Academy and the dedicated account manager.
Trading 212
Investors who buy a lot of overseas shares, since the 0.15% FX fee is well under XTB’s 0.5%. Also anyone who wants a SIPP alongside their ISA in the same app.
XTB
ISA investors who keep a meaningful cash balance, since XTB pays interest on uninvested cash, quoted at 4.00% on GBP in October 2026. It also suits regular ETF investors who want automated Investment Plans, and anyone who values a dedicated account manager.
Trading 212
Anyone who needs funds, bonds or pension drawdown, or who wants deeper research tools. The CFD account is not a sensible place for a beginner to start.
XTB
Anyone who needs a pension, Junior ISA or Lifetime ISA, since XTB offers none of them. Frequent buyers of US shares will also pay more in currency conversion than at Trading 212.
Trading 212
Zero commission is real, and the 0.15% FX fee is the main running cost. Uninvested cash in the Invest account earned 3.8% AER on GBP as of 5 August 2026 once interest was enabled, and the Cash ISA paid 3.6% AER variable on the same date.
XTB
On commission and platform fees the two are level for most investors. The trade off is XTB’s higher 0.5% FX fee against its interest on cash, so which is cheaper depends on how much you hold overseas and how much sits uninvested. Our compound interest calculator shows how small differences add up over time.
Compare the yearly cost of Trading 212, XTB and other UK platforms with our broker fees calculator.
Cons
Pros
Cons
Pros
Trading 212
For most UK investors building a stocks and ETF ISA with overseas holdings, Trading 212 is the cheaper platform to run. Both charge no commission, but Trading 212’s 0.15% FX fee is well under XTB’s 0.5%, and it adds a SIPP in the same app.
XTB
XTB is the stronger choice if you keep a larger cash balance waiting to be invested, if you mainly buy sterling assets so the FX gap matters less, or if you value a dedicated account manager and structured learning. Its flexible ISA and Investment Plans make it a very capable low cost alternative.
Trading 212
You buy US listed shares regularly, or you want an ISA and a SIPP under one login. The detail is in our Trading 212 review, and our Trading 212 vs eToro and Trading 212 vs Vanguard comparisons cover other common alternatives.
XTB
You want interest on idle cash, automated ETF plans and a named contact at your broker. Our XTB review covers each feature, our eToro vs XTB comparison looks at XTB’s ISA from another angle, and our broker matching tool can narrow the field. You can also browse all our broker comparisons.
Risk disclaimer
This article is for general information and education. It is not personal financial advice and does not take account of your circumstances. When you invest, your capital is at risk and you may get back less than you put in. Past performance is not a guide to future returns.
Both platforms also offer CFDs, which are leveraged products that cannot be held in an ISA and sit outside the main scope of this comparison. Trading 212 discloses that 77% of retail investor accounts lose money when trading CFDs with this provider; XTB discloses 74%.
Tax treatment depends on your individual circumstances and ISA and pension rules may change. If you are unsure whether a product is right for you, seek advice from an FCA authorised adviser.
Fees and product details are taken from our Trading 212 and XTB reviews and XTB's UK website, checked between August and October 2026, and may have changed since. Always confirm current terms on the provider's own website.
No commission | 0.15% FX fee
Capital at risk.
For most investors who buy overseas shares, yes. Neither charges commission on shares and ETFs at typical investing levels, and neither charges a platform fee on the ISA. The difference is currency conversion: 0.15% at Trading 212 against 0.5% at XTB, so £10,000 of US shares costs £15 against £50 each way. If you mainly buy sterling assets and keep cash uninvested, XTB's interest can tip the balance. Comparing XTB vs Trading 212 on headline commission alone, both are zero.
Both offer a free, flexible Stocks and Shares ISA with commission-free shares and ETFs. Trading 212 is cheaper for overseas holdings and lets you hold a SIPP in the same app. XTB pays interest on uninvested cash and offers automated Investment Plans. Since April 2024 you can pay into more than one stocks and shares ISA in the same tax year, so using both is an option.
Trading 212 does. Its SIPP received FCA authorisation in February 2026, is operated by Platform One and has no platform fee or dealing charge, although there is no drawdown option yet. XTB does not offer a SIPP, a Junior ISA or a Lifetime ISA.
XTB quoted 4.00% on GBP on its UK website in October 2026, calculated daily and paid monthly. Trading 212 quoted 3.8% AER on GBP for cash in the Invest account as of 5 August 2026, paid daily once you enable it, and its Cash ISA paid 3.6% AER variable on the same date. XTB's flexible Cash ISA paid 4% AER variable from 1 May 2026. Rates are variable on both, so check the live figures. Trading 212 holds some interest-earning cash in qualifying money market funds, which count as investments rather than bank deposits for FSCS purposes.
Both UK entities are authorised and regulated by the Financial Conduct Authority: Trading 212 UK Ltd under firm reference number 609146 and XTB Limited under 522157. Investments are covered by the FSCS up to £85,000 at both, and Trading 212's uninvested cash at partner banks is covered up to £120,000 per bank. Neither protects you against investment losses.
Both are beginner friendly. Trading 212 is simpler if you just want to buy shares and ETFs cheaply from £1 and automate with Pies. XTB suits beginners who want structured lessons, a £100,000 demo account and a named account manager, as long as they take care to buy the share rather than its CFD version. Both CFD accounts are best avoided while you are learning.
Yes. Trading 212 does not charge for transfers in or out. XTB accepts ISA transfers in, arranged through the app, which can take up to 30 days. XTB does not yet accept Cash ISA transfers in, although it says this is coming soon. Always use the receiving provider's transfer process rather than withdrawing and reinvesting, or you lose that part of your allowance. Our ISA transfer guide explains the steps.
Trading 212 does not. XTB charges £10 a month on a general account after 12 months without a trade and 90 days without a deposit, but never on the ISA. Making one trade or deposit within those windows avoids it.
Compare the best UK brokers side by side.
Disclaimer
The information provided on this page and throughout the website is for general information purposes only and does not constitute financial advice. It is important that you conduct your own research and consider your own personal circumstances before making any investment decisions.
While we strive to provide accurate product information at the time of publication, the information may be subject to change by the provider at any time. Please always verify the product information before making any decisions. Past results do not guarantee future profits.
If you use some of the links on Your Wallet Manager, we may receive a small fee from our partners, supporting the website’s free usage. However, please be assured that our editorial content is never influenced by these links. We include them to help us keep the lights on and to support our mission of helping people make informed financial decisions regarding their wallet’s most important spendings.
Thank you for your understanding and support!
Adding {{itemName}} to cart
Added {{itemName}} to cart