





Bank Rate Rise 2026: What 4% Means For Savers And Investors
The Bank of England raised Bank Rate from 3.75% to 4% on 5 November 2026, the first increase since August 2023. Here is what the decision actually reaches…
7 min readRead guide

Compare platforms
Head-to-head broker comparisons
Still deciding?
See which platforms fit your goals
Broker reviews
Choose a UK investing platform
Our top picks
Not sure which platform suits you?
Answer a few questions and see which UK platforms fit your goals.
Broker reviews
Choose a UK investing platform
 eToro
 IG
 Interactive Brokers
 Freetrade
 Vanguard UK
 Trading 212
 AJ Bell
 Trading.com
 Lightyear
 Webull UK
 XTB UK
 Robinhood UK
 Hargreaves Lansdown
 Interactive Investor
 InvestEngine
Every review covers fees, account types, safety and FCA regulation, and is updated as providers change their pricing.
Knowledge hub
Guides for UK investors
Topics
Ready to start investing?
Answer a few questions and see which UK platforms fit your goals.
Now J.P. Morgan Personal Investing: returns, fees, accounts and our verdict
By Dimitar Kanazirski, Editor-in-chief
Published: | Fact-checked by: David Katzarov | Last updated:
What will you find in this review:
In this YourWalletManager Nutmeg review, we look at one of the UK's best known digital wealth managers. In November 2025 Nutmeg was renamed J.P. Morgan Personal Investing, so you may see either name used. It is the same company, the same portfolios and the same investment team.
Our verdict in brief
Nutmeg, now J.P. Morgan Personal Investing, is one of the most established ways in the UK to have your money managed for you. You pick a risk level and an investment style, and its team does the rest, from £500 or £100 for a Lifetime or Junior ISA.
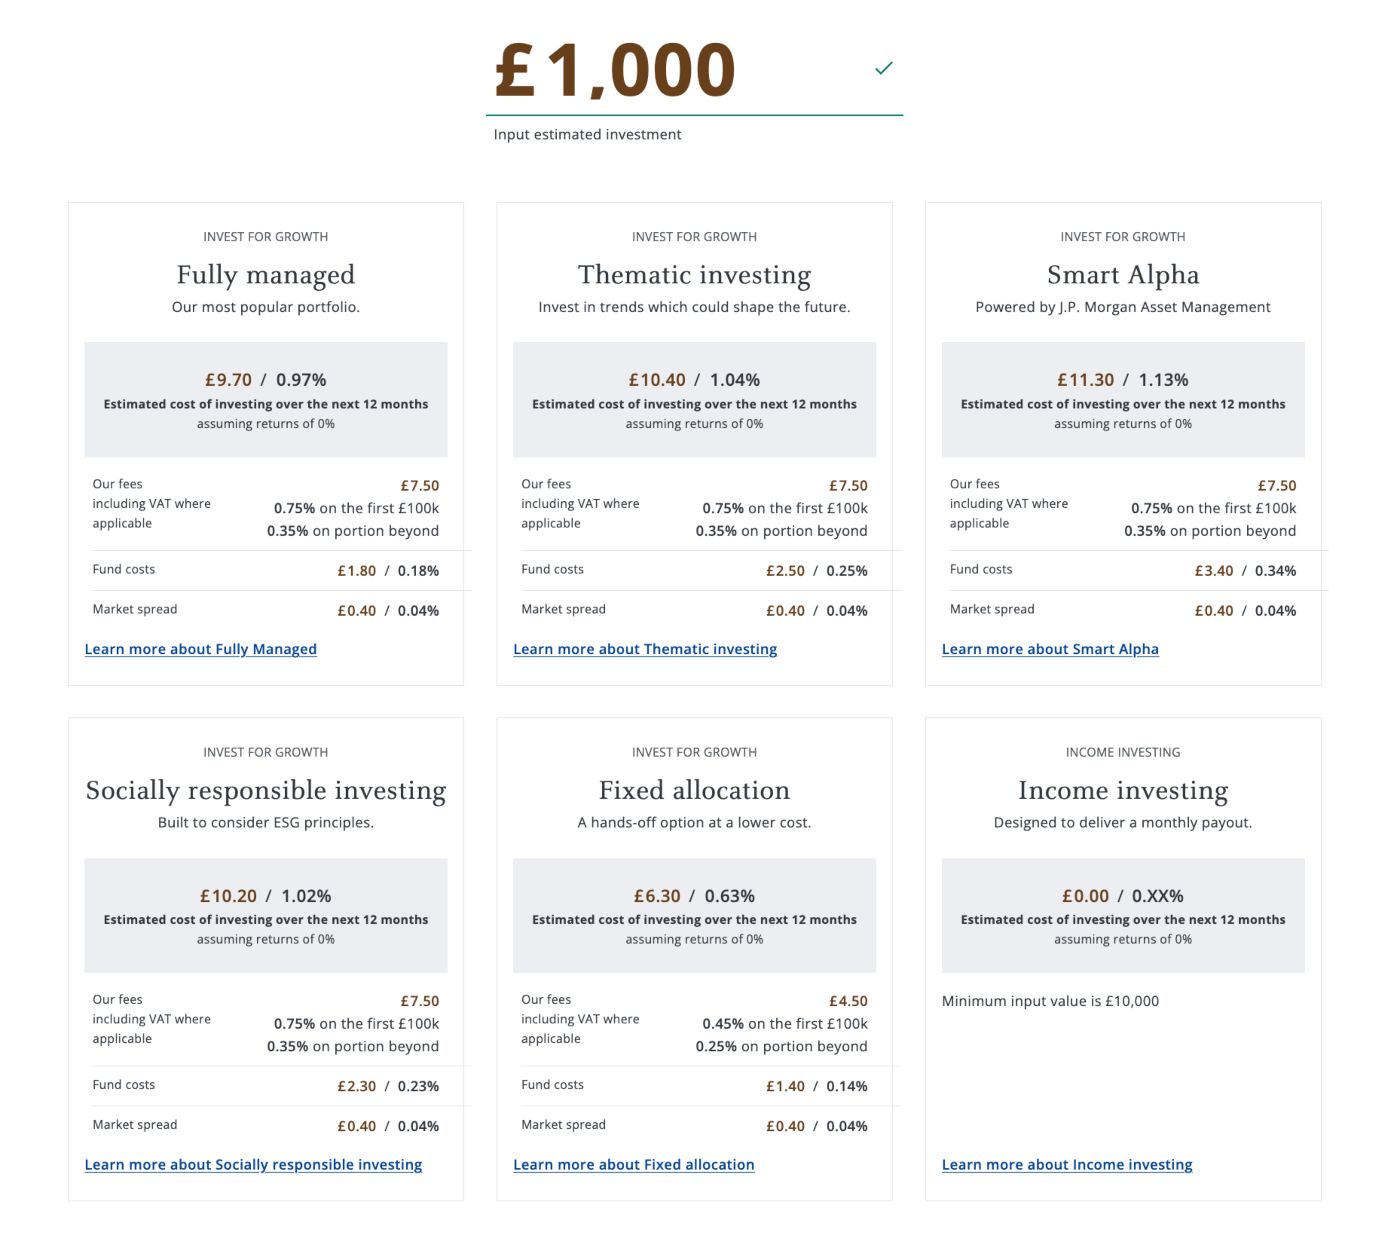
Costs are clear but not cheap: 0.75% a year on your first £100,000 for most styles, or 0.45% for Fixed Allocation, plus fund costs and spread. On a £20,000 Fully Managed pot it estimates about 0.97% a year in total.
Its Fully Managed range has a 14-year published track record that has matched or beaten its industry benchmark at every comparable risk level. It suits hands-off investors; if you want to choose your own investments, a DIY platform will cost less.
Pros
Cons
It's important to note that this review is tailored to UK residents.
What you will find in this review:
Nutmeg was founded in 2012 and became the UK's first online discretionary investment manager. JPMorgan Chase acquired the business in 2021, and after several years of investment it was rebranded to J.P. Morgan Personal Investing on 3 November 2025.
Setting up a portfolio takes under ten minutes. The minimum opening deposit is £500 for a General Investment Account, Stocks and Shares ISA or pension, or £100 for a Lifetime ISA or Junior ISA.
On 3 November 2025 Nutmeg began trading as J.P. Morgan Personal Investing. If you held a Nutmeg account there was nothing to do: portfolios, risk levels and the investment team all carried across, and the app and online dashboard were simply rebranded. The FCA firm reference number is unchanged at 552016, so this is the same regulated company under a new name.
The change had been coming for a while. JPMorgan Chase bought Nutmeg in 2021, and the years since brought a Thematic Investing style, a much larger advice and guidance team, and a second partnership with J.P. Morgan Asset Management that produced Income Investing. The rebrand brings the platform formally under the parent brand.
Three things are genuinely new. A wealth planner tool gives you a single view of your total wealth alongside suggestions for closing the gap to your goals. Clients with more than £250,000 invested now get a dedicated relationship manager. And during 2026 a full DIY investment platform is due to launch, which will let clients buy and sell their own shares, bonds and funds for the first time.
| 🗺️ Supported Countries | The United Kingdom |
| 📊 Management fees | 0.75% to 0.35% managed styles; 0.45% to 0.25% Fixed Allocation |
| 💲 Market spread | About 0.04% a year |
| ⏳ Inactivity fee | £0 |
| 🏧 Withdrawal fee | £0, though LISA, JISA and pension rules apply |
| 💵 Minimum Deposit | £500 for GIA, pension and ISA / £100 for Lifetime or Junior ISA / £10,000 for Income Investing |
| 💡 Products offered | GIA, Personal Pension, ISA, LISA, JISA |
| 🎮 Demo Account | No |
| 📜 Regulatory entities | FCA (FRN 552016) |
You can start with £500 in a General Investment Account, Stocks and Shares ISA or Personal Pension, or £100 in a Lifetime ISA or Junior ISA.
There are six investment styles to choose from: Fully Managed, Smart Alpha, Socially Responsible, Thematic Investing, Income Investing and Fixed Allocation. Each is built mainly from exchange traded funds and managed for you.
Annual management fees are tiered. The managed styles cost 0.75% on your first £100,000 and 0.35% above that, while Fixed Allocation costs 0.45% on the first £100,000 and 0.25% above it (checked 11 October 2026 and subject to change).
There are six investment styles, all built mainly from exchange traded funds and managed for you. Five of them work inside any account, from a General Investment Account to a Stocks and Shares ISA, Lifetime ISA, Junior ISA or Personal Pension. Income Investing is the exception: it is only available in a Stocks and Shares ISA or General Investment Account. The table below shows what each style costs.
| Investment style | Management fee | Fund costs | Market spread | Est. total a year |
|---|---|---|---|---|
| Fully Managed | 0.75% (0.35% above £100k) | 0.18% | 0.04% | 0.97% |
| Smart Alpha | 0.75% (0.35% above £100k) | 0.34% | 0.04% | 1.13% |
| Socially Responsible | 0.75% (0.35% above £100k) | 0.23% | 0.04% | 1.02% |
| Thematic Investing | 0.75% (0.35% above £100k) | 0.25% | 0.04% | 1.04% |
| Income Investing | 0.75% (0.35% above £100k) | 0.39% | 0.04% | 1.18% |
| Fixed Allocation | 0.45% (0.25% above £100k) | 0.14% | 0.04% | 0.63% |
Totals are J.P. Morgan Personal Investing’s own estimate for a £20,000 pot over 12 months, assuming 0% returns, including VAT where applicable. Source: Our fees, checked 11 October 2026.
The flagship option, with ten risk levels to choose from. A team of investment professionals monitors markets and adjusts your asset mix over time, so you are not left holding a portfolio that quietly drifts away from its target. J.P. Morgan estimates the total yearly cost on a £20,000 pot at about 0.97%.
Built in partnership with J.P. Morgan Asset Management for investors who want to try to beat the market rather than simply track it. It blends index funds with actively managed J.P. Morgan funds, which is why its underlying fund charges run higher than the Fully Managed range. Smart Alpha is a trade mark of Schroders plc and is used under licence. J.P. Morgan estimates the total yearly cost on a £20,000 pot at about 1.13%.
A lower cost, rules based option. The asset mix is set in advance and rebalanced automatically rather than actively adjusted, which is why it carries the cheapest management fee on the platform at 0.45% falling to 0.25%. J.P. Morgan estimates the total yearly cost on a £20,000 pot at about 0.63%.
For investors who want their money to reflect their values. It tilts towards companies with stronger environmental, social and governance practices and screens out several controversial sectors. J.P. Morgan estimates the total yearly cost on a £20,000 pot at about 1.02%.
Added after the JPMorgan acquisition, Thematic Investing targets the long-term structural trends reshaping the economy rather than tracking the market as a whole. It sits at the same 0.75% management fee as the other managed styles, though because it launched relatively recently it has a shorter performance record than the longer-established options. J.P. Morgan estimates the total yearly cost on a £20,000 pot at about 1.04%.
The newest style, launched through a second partnership with J.P. Morgan Asset Management. Rather than aiming purely for capital growth, it holds dividend-focused ETFs and pays you a monthly income while still seeking to grow your capital. It is also the most restricted option on the platform: the minimum investment is £10,000 rather than £500, and it is available only inside a Stocks and Shares ISA or General Investment Account, not a pension, Lifetime ISA or Junior ISA. Income is not guaranteed. J.P. Morgan estimates the total yearly cost on a £20,000 pot at about 1.18%.
Every investment style except Income Investing works inside each of the accounts below, so you choose the account for your goal and then how the money is managed. Here is what each one offers.
Open with £500 and pay in up to your £20,000 annual ISA allowance. All six styles are available, including Income Investing. The catch is that the ISA is not flexible: money you withdraw still counts towards that year’s allowance if you pay it back in. You can transfer existing ISAs in.
A stocks and shares Lifetime ISA you can open with £100 if you are 18 to 39. You can pay in up to £4,000 a year until you turn 50, and the government adds a 25% bonus worth up to £1,000 a year. Withdrawals are free for a first home costing £450,000 or less, from age 60, or if you are terminally ill; otherwise a 25% government charge applies. You can transfer an existing Lifetime ISA in through the website, though not the app, and transfers usually take around three weeks.
A stocks and shares Junior ISA you can open with £100, with up to £9,000 a year paid in on top of your own allowance. J.P. Morgan Personal Investing requires the child to be under 16 when the account is opened. The money belongs to the child, cannot be withdrawn until 18, and the account then becomes an adult Stocks and Shares ISA in their name. Child Trust Funds can be transferred in.
The Personal Pension opens with £500 and adds 20% tax relief to your contributions, up to £60,000 a year or 100% of your earnings, whichever is lower. Higher and additional rate taxpayers can claim more through their tax return. It is managed in the same styles as the ISA rather than being a self-select SIPP, so you choose a style and risk level, not individual funds. You can transfer in old workplace and personal pensions, and take money out flexibly from 55, rising to 57 from April 2028, with up to 25% tax free. The scheme is operated and administered by Embark Services Limited.
A taxable account with the same £500 minimum, useful once your ISA allowance is used up. You can withdraw whenever you need to.
J.P. Morgan Personal Investing publishes the full track record of its Fully Managed portfolios, the original style Nutmeg launched with, for each of its ten risk levels. The figures below come from that track record and run from launch on 30 September 2012 to 30 September 2026.
They are composite returns: the average of every client account at each risk level, weighted by account size, after management fees, fund costs and market spread. In other words, charges have already been taken off.
| Risk level | Annualised since launch | Total since launch | Annualised, last 10 years | Last 12 months |
|---|---|---|---|---|
| 1 (lowest) | 1.4% | +20.8% | 1.3% | +4.1% |
| 2 | 2.5% | +41.6% | 2.2% | +5.3% |
| 3 | 3.2% | +54.8% | 2.8% | +7.0% |
| 4 | 3.9% | +71.0% | 3.4% | +8.3% |
| 5 | 4.8% | +92.3% | 4.3% | +10.5% |
| 6 | 5.7% | +117.0% | 5.4% | +12.5% |
| 7 | 6.9% | +155.0% | 6.7% | +14.5% |
| 8 | 8.0% | +194.5% | 7.9% | +16.8% |
| 9 | 9.2% | +241.0% | 9.1% | +18.9% |
| 10 (highest) | 9.8% | +270.7% | 9.7% | +18.9% |
Past performance is not a reliable indicator of future returns. The value of your investments can go down as well as up, and you may get back less than you put in. These are average client returns; your own result depends on when you invested, how much you paid in or took out, and the fee rate on your account.
Source: J.P. Morgan Personal Investing (formerly Nutmeg), Fully Managed track record, figures to 30 September 2026, accessed 10 October 2026. Annualised returns are shown as a compound yearly rate. ° Figures from Asset Risk Consultants (ARC), as published by J.P. Morgan Personal Investing.
Higher risk levels have grown faster, with bigger falls along the way. Risk level 10 has returned 9.8% a year since launch, against 1.4% a year at risk level 1. The ride has been bumpier than the long-run averages suggest: risk level 6, the middle of the range, lost 12.6% in 2022 and 7.1% in 2018 before recovering.
Every level with a comparable industry benchmark has matched or beaten it. J.P. Morgan Personal Investing compares each level with indices from Asset Risk Consultants (ARC), which track discretionary wealth managers after fees. Since launch, risk level 6 returned 5.7% a year against 4.8%° for the ARC Sterling Balanced Asset index, and risk level 10 returned 9.8% a year against 7.2%° for the ARC Sterling Equity Risk index. Risk level 5 matched its benchmark at 4.8% a year, and ARC has no equivalent index for risk levels 1 and 2.
ARC indices measure traditional wealth managers rather than low-cost index funds, so they are a useful yardstick but not the only one. The track record also covers Fully Managed only. Smart Alpha, Socially Responsible, Thematic Investing and Fixed Allocation each have their own track record, so these figures do not apply to them.
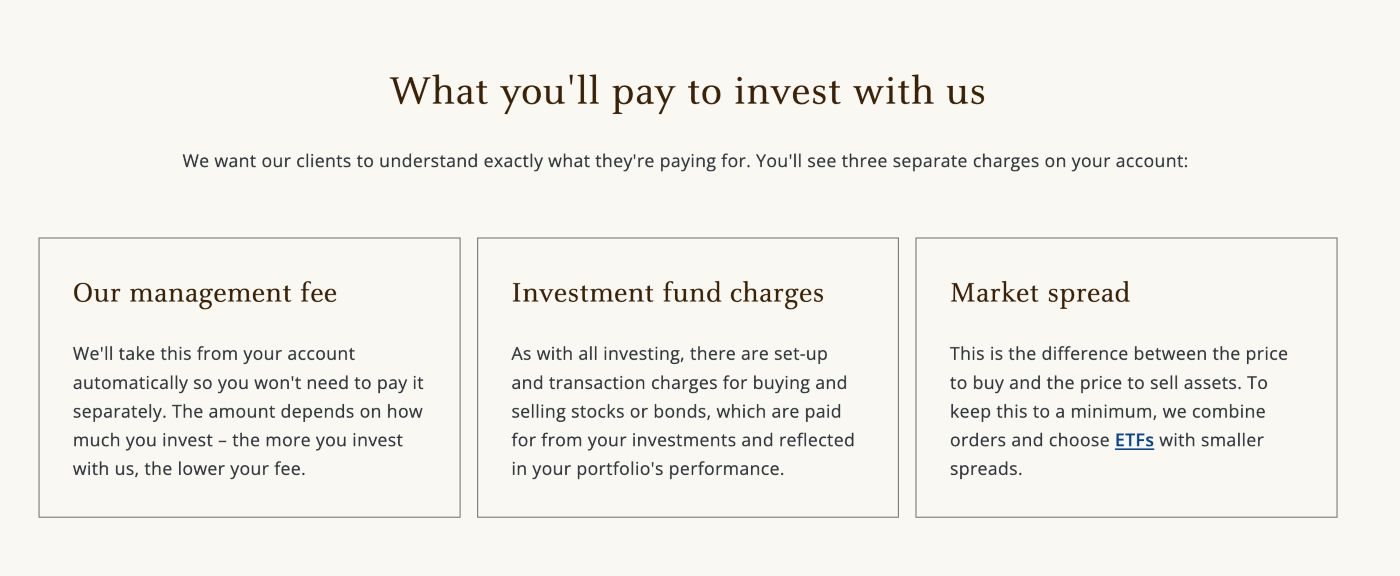
J.P. Morgan Personal Investing charges an annual management fee that falls as your pot grows. For the managed styles, meaning Fully Managed, Smart Alpha, Socially Responsible, Thematic Investing and Income Investing, you pay 0.75% on your first £100,000 and 0.35% on anything above that. Fixed Allocation is priced separately at 0.45% on the first £100,000 and 0.25% above it.
The fee is calculated daily and taken automatically from your account on the first working day of each month. There are no set-up fees, no dealing commissions, no exit fees and no charge to withdraw your money.
Your money is invested largely through exchange traded funds, and those funds carry their own annual charges set by the fund providers rather than by the platform. J.P. Morgan Personal Investing’s own estimates put them at 0.14% a year for Fixed Allocation, 0.18% for Fully Managed, 0.23% for Socially Responsible, 0.25% for Thematic Investing, 0.34% for Smart Alpha and 0.39% for Income Investing. Fund costs are reflected in your portfolio’s performance rather than billed to you separately.
There is also a small gap between the price to buy and the price to sell each fund, known as the market spread. J.P. Morgan Personal Investing estimates this at about 0.04% a year, and the platform combines client orders and favours funds with tighter spreads to keep it down.
One further point worth knowing: uninvested cash sitting in your pots earns interest at the Bank of England base rate minus 0.75%. Cash-only pots and money in transit earn nothing, so it pays to stay invested.
The platform is operated by J.P. Morgan Personal Investing Limited, which is authorised and regulated by the Financial Conduct Authority under firm reference number 552016. It is registered in England and Wales as company number 07503666, with its registered office at 25 Bank Street, Canary Wharf, London E14 5JP.
Worth noting for anyone worried about the rebrand: the firm reference number is unchanged. This is the same regulated entity that traded as Nutmeg, under a new name, rather than a new company you are moving to.
Client money and investments are held separately from the firm’s own assets, and holdings are registered through a nominee arrangement so your ownership stays clearly recorded. If the firm were to fail with a shortfall in client assets, the Financial Services Compensation Scheme protects eligible investment claims up to £85,000 per person.
That protection covers the platform failing, not market losses. The value of your portfolio can still fall as well as rise, and you may get back less than you put in.
Now trading as J.P. Morgan Personal Investing, the platform combines a decade of Nutmeg's technology with the scale and oversight of one of the world's largest investment firms.
A user-friendly interface and comprehensive setup options cater to novice investors, easing them into the investment process seamlessly.
The intuitive mobile and desktop platforms provide a hassle-free experience, allowing users to manage their investments effortlessly.
Between the six investment styles and the ten Fully Managed risk levels, there is a good range of choice without the paralysis of picking individual funds yourself.
The account range is broader than most robo-advisors, and the Lifetime ISA and Junior ISA are genuinely useful additions that several rivals do not offer at all.
Start your investing journey with J.P. Morgan Personal Investing, formerly Nutmeg today!
Nutmeg is well established and FCA regulated, but a managed service is not the right fit for everyone. These are the limits worth weighing before you open an account.
A minimum initial deposit requirement of £500 may pose a barrier for some investors, limiting accessibility.
At 0.75% on the first £100,000 plus fund costs, you pay noticeably more than on a self-directed platform. You are paying for the management, so the question is whether you want that service.
Money you withdraw from the ISA still counts towards your annual allowance for that tax year, so replacing it later uses up more of your allowance. Several rivals now offer a flexible ISA instead.
A few smaller points are also worth knowing. Uninvested cash earns the Bank of England rate minus 0.75%, and cash-only pots earn nothing. Income Investing needs £10,000 and is only available in an ISA or general account. The Junior ISA must be opened before your child turns 16. J.P. Morgan has said a DIY investing service is on the way, but it had not launched when we checked in October 2026.
If any of these rule Nutmeg out for you, the alternatives below or our Find My Broker quiz can point you to a better fit.
Nutmeg is likely to suit you if you:
You may be better served elsewhere if you:
The client services team is available by phone Monday to Friday. Current opening hours are listed on the contact page, and there is no phone support at weekends.
For anything involving account details, you can send a secure message from your online dashboard rather than ordinary email, which keeps sensitive information out of your inbox.
Live chat runs in the same weekday hours as phone support and suits shorter questions where you do not need to send documents.
In our examination of the customer service available, it’s evident that accessibility is a top priority. They’ve strategically placed a customer service option on every page of their website which is available during regular business hours, providing multiple channels for communication including phone, email, and in-app chat.
Customer service has long been a weak spot across the investment industry, and it is one area where this platform has generally scored well with users. Support is weekday only, so there is no cover at weekends, but response times during the week are usually quick and the team can handle account level queries rather than just general questions.
An intriguing feature observed on the website is the opportunity for investors to schedule face-to-face meetings with advisors at their London office. While the logistics of scheduling such meetings remain unclear, it underscores the dedication to enhancing customer satisfaction through personalized interactions.
Alongside the usual channels, every client can book free financial guidance sessions, and clients with more than £250,000 invested are given a dedicated relationship manager. Paid-for restricted financial advice is available separately if you want a formal recommendation.
At first glance, the account setup process may seem a bit more involved compared to other platforms.
You start by entering your email address and creating a secure password that meets their requirements. Personal details like name, address, and National Insurance number are required afterwards.
It is important to note that, unfortunately, Nutmeg accounts are only available to UK residents.
Nationality and bank details must also be provided, although no charges are incurred; this information is solely for identity verification and withdrawal processing.
Users must read and accept the terms and conditions, with key points highlighted for clarity.
Following this, a series of questions helps determine a suitable risk level for the investment portfolio, which can be adjusted later. For instance, with a stocks and shares ISA, users can invest up to £20,000 tax-free annually, with no setup or exit fees.
The minimum deposits as mentioned above for each account type are as follows:
Once personal details and risk assessment are complete, users can name the investment pot, set a target amount, and choose a timeline for investment.
They can also select an investment style, such as fully managed, smart alpha, socially responsible, or fixed allocation, each with its unique fee structure.
The risk and reward balance are then set, which users can manually edit if desired. A plot summary provides a comprehensive overview of the investment pot, including contributions, timeline, styles, and risks.
Users can view projections of their investment’s value over time and understand the associated costs and charges. Additionally, they can monitor the portfolio’s allocation and historical performance from the dashboard.
A managed service is not the only way to invest, and a cheaper or more hands-on platform may suit you better. These are the alternatives we would look at first, depending on what matters most to you.
Best low-fee alternative
Trading 212
No commission or platform fee on shares and ETFs, plus an ISA and a SIPP. Best if you are happy to choose your own investments.
Capital at risk.

Best for beginners
InvestEngine
No platform fee on DIY ETF portfolios, with ready-made managed portfolios if you would rather have help.
Capital at risk.

Closest like-for-like alternative
Hargreaves Lansdown
A wide fund range and ready-made portfolios across ISAs, pensions and Junior ISAs, with far more choice than Nutmeg.
Capital at risk.
Low-cost ready-made funds
Vanguard
Vanguard’s own LifeStrategy and target retirement funds in an ISA, SIPP or Junior ISA, from one of the world’s largest fund managers.
Capital at risk.
For experienced investors
Interactive Brokers
A Nasdaq-listed global broker with low dealing costs and access to markets worldwide, better suited to confident, hands-on investors.
Capital at risk.
Every platform here is authorised by the FCA. For a direct head-to-head on cost and choice, see our Nutmeg vs Hargreaves Lansdown comparison, or answer a few questions in our Find My Broker quiz.
Not a self-select SIPP. Its pension is a Personal Pension: you choose an investment style and risk level and the team manages it for you. You can open one with £500, get 20% tax relief added to your contributions, and transfer in other pensions.
Fully Managed portfolios are actively adjusted by the investment team as markets change. Fixed Allocation portfolios follow a set asset mix and are rebalanced automatically. That makes Fixed Allocation cheaper: J.P. Morgan estimates about 0.63% a year in total on a £20,000 pot, against about 0.97% for Fully Managed.
No. Money you withdraw still counts towards your ISA allowance for that tax year, so paying it back in uses up more of your allowance.
No. J.P. Morgan Personal Investing requires the child to be under 16 when the Junior ISA is opened. Existing Junior ISAs and Child Trust Funds can be transferred in.
To 30 September 2026, Nutmeg's Fully Managed portfolios returned between 1.4% a year at risk level 1 and 9.8% a year at risk level 10 since launch in September 2012, after fees. The middle of the range, risk levels 5 and 6, returned 4.8% and 5.7% a year. Past performance is not a reliable indicator of future returns.
Risk level 10 has the strongest record, at 9.8% a year since launch and 9.7% a year over the ten years to 30 September 2026. It also carries the most risk, so it can fall further when markets drop. Lower risk levels have grown more slowly but are designed to be steadier.
Nutmeg built its reputation on making managed investing simple, and as J.P. Morgan Personal Investing that core proposition is intact while the resources behind it have grown. If you want a diversified portfolio looked after for you, across a genuinely broad set of tax wrappers including a Lifetime ISA and Junior ISA, it remains one of the strongest options in the UK.
The trade-offs are straightforward. At 0.75% on your first £100,000 plus fund charges, you pay more than on a self-directed platform, the Stocks and Shares ISA is not flexible, and until the DIY platform arrives during 2026 you cannot pick individual shares. If you would rather choose your own investments, a low cost DIY platform will serve you better. Our Nutmeg vs Hargreaves Lansdown comparison sets that choice out side by side on fees, account types and investment range. If you want the decisions handled, the fee buys you a well run service. As always, only invest money you can afford to leave alone for the long term.
Other recommended brokers
This review follows the same process we apply to every broker, so you can see what the verdict above is actually based on.
Don't forget to visit our Knowledge Hub for more useful information on all things personal finance
Bank Rate Rise 2026: What 4% Means For Savers And Investors
The Bank of England raised Bank Rate from 3.75% to 4% on 5 November 2026, the first increase since August 2023. Here is what the decision actually reaches…
Nvidia CEO Shock Exit: How Does This Affect UK Investors?
Jensen Huang, who co-founded Nvidia in 1993 and ran it for 33 years, resigned as president and chief executive on Thursday 12 November 2026, with immediate effect. The…
Inherited Pension Tax 2027: What Changes For Your Family
The two year rule that could turn a tax free inherited pension into taxable income ended on 28 October 2026. From 6 April 2027, most unused pension funds…
About YWM
For general information only, not financial advice. Investing puts your capital at risk.
The information provided on this page and throughout the website is for general information purposes only and does not constitute financial advice. It is important that you conduct your own research and consider your own personal circumstances before making any investment decisions.
While we strive to provide accurate product information at the time of publication, the information may be subject to change by the provider at any time. Please always verify the product information before making any decisions. Past results do not guarantee future profits.
If you use some of the links on Your Wallet Manager, we may receive a small fee from our partners, supporting the website's free usage. However, please be assured that our editorial content is never influenced by these links. We include them to help us keep the lights on and to support our mission of helping people make informed financial decisions regarding their wallet’s most important spendings.
Thank you for your understanding and support!
Our top picks
All reviews
Reviews hubHead-to-head comparisons
Fees, account types and features side by side.
Welcome offers
Best providers
Free tools
Categories
Knowledge hubAdding {{itemName}} to cart
Added {{itemName}} to cart