Bank Rate Rise 2026: What 4% Means For Savers And Investors
The Bank of England raised Bank Rate from 3.75% to 4% on 5 November 2026, the first increase since August 2023. Here is what the decision actually reaches…
Compare platforms
Head-to-head broker comparisons
Still deciding?
See which platforms fit your goals
Broker reviews
Choose a UK investing platform
Our top picks
Not sure which platform suits you?
Answer a few questions and see which UK platforms fit your goals.
Broker reviews
Choose a UK investing platform
eToro
Interactive Brokers
Freetrade
Vanguard UK
Trading 212
AJ Bell
Lightyear
Webull UK
Robinhood UK
Hargreaves Lansdown
Interactive InvestorEvery review covers fees, account types, safety and FCA regulation, and is updated as providers change their pricing.
Knowledge hub
Guides for UK investors
Topics
Ready to start investing?
Answer a few questions and see which UK platforms fit your goals.
Overview, highlights & more!
By David Katzarov, Editor
Published: | Fact-checked by: Dimitar Kanazirski | Last updated:
In this YourWalletManager Interactive Investor review, we look at the UK's original flat fee investment platform. Interactive Investor, almost always shortened to ii, has been running since 1995 and is now the second largest direct platform in the country behind Hargreaves Lansdown.
The thing that makes ii different is how it charges. Nearly every other UK platform takes a percentage of your portfolio, so your bill grows as your investments grow. ii charges a flat monthly fee instead, which does not move whether you hold £5,000 or £500,000.

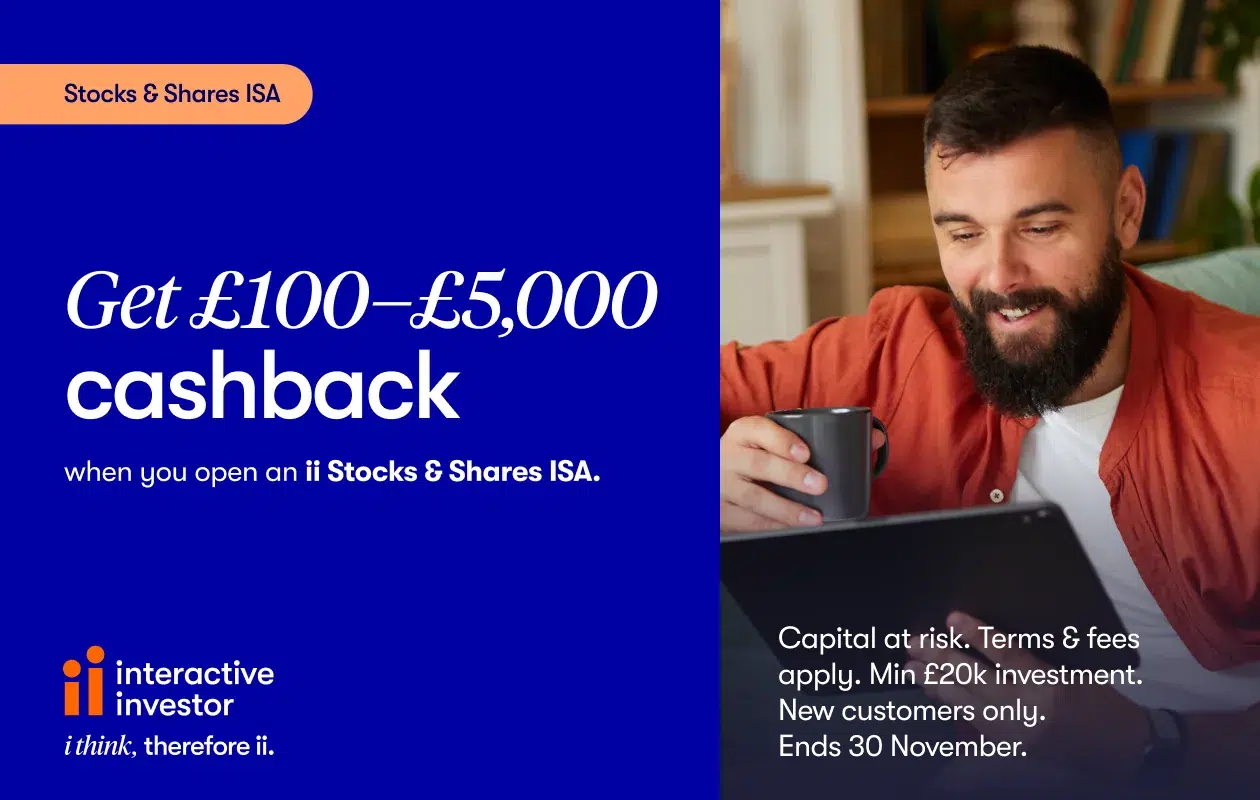
Current welcome offer, ends 30 November 2026
New ii customers who open a Stocks and Shares ISA, SIPP or Trading Account by 30 November and add at least £20,000 can get cashback paid into their ii Trading Account.
Capital at risk. Terms and fees apply.
ii has restructured its pricing into three plans: Core at £5.99 a month, Plus at £14.99 and Premium at £39.99. Which one you are on depends partly on your portfolio size, because the Core plan is capped at £100,000.
That flat fee model is the whole argument for and against ii. On larger portfolios, particularly fund portfolios, it can work out cheaper than a percentage platform. On a small pot, you are paying at least £71.88 a year whether you invest actively or leave the account untouched.
| 🗺️ Supported Countries | The United Kingdom |
| 📊 Platform fee | Flat monthly fee from £5.99 |
| 💲 UK and US share dealing | £3.99 per trade, £2.99 on Premium |
| ⏳ Inactivity fee | £0 |
| 🏧 Withdrawal fee | £0 next day in GBP or EUR |
| 💵 Minimum Deposit | £0, regular investing from £25 per month |
| 💡 Products offered | Trading Account, ISA, Managed ISA, SIPP, JISA |
| 🎮 Demo Account | No |
| 📜 Regulatory entities | FCA (FRN 141282) |
ii covers the mainstream UK wrappers, though the Junior ISA is only available on the Plus and Premium plans rather than on Core.
Because the fee is flat rather than a percentage, the effective cost as a share of your portfolio falls the more you hold. That is the opposite of how most UK platforms work.
All subscription prices, dealing charges and key plan benefits in this review were checked against Interactive Investor's published charges on 23 October 2026. Rates and features can change, so check ii's current fee schedule before opening or upgrading an account.
ii works differently from most platforms. Rather than charging per account, you pick one of three monthly plans, and that plan gives you access to every account type you are eligible for. You can open one account and add the others later at no extra cost.
The entry plan, and where every new customer starts. It covers a Trading Account, Stocks and Shares ISA, Managed ISA and Personal Pension, plus research, multi currency investing and the ii Community forum. Fund and UK or US share trades cost £3.99 each, other international shares are £9.99, and foreign exchange is charged at 0.75%. The catch is the £100,000 portfolio limit: pass it and you move up to Plus automatically.
Plus removes the portfolio cap and adds the features most families want. You get free Junior ISAs for all your children, up to five free family accounts holding up to £100,000 each, and £3.99 of monthly trading credit, worth one UK or US share trade. Fund dealing drops to £1.49, UK and US share trades stay at £3.99, other international shares fall to £7.99, and foreign exchange drops to 0.25% on anything above £50,000.
Premium is aimed at more active investors and households using ii across several accounts. It costs £39.99 a month, or £479.88 a year, and now includes £29.90 of monthly trading credit, equivalent to ten UK or US share trades at £2.99 each. The credit lasts 31 days and unused credit does not roll over, so it is not a discount on the subscription. Fund trades and dividend reinvestment are free, other international shares cost £5.99 and foreign exchange is a flat 0.25%. Premium also includes ii360 access, waives the usual £30 a month charge on eligible Business Accounts, and allows unlimited family accounts with up to £250,000 each. These extras only add value if you will actually use them.
ii360 is ii's separate advanced investing platform, designed for experienced investors who want deeper research, a customisable workspace and more control over their strategies. It is included with Premium, or costs an extra £20 a month on Core and Plus. Access and dealing costs are separate questions: ii states that Premium trading rates and free trades do not apply to an ii360 account, which has its own fee schedule. It is a useful extra for experienced investors rather than a reason for beginners to pay more.
Every plan includes a Trading Account, a Stocks and Shares ISA, a Managed ISA, a Personal Pension and the Managed Portfolios range. The Junior ISA is the exception, available only on Plus and Premium. There is also a Joint Trading Account, charged separately at £14.99 a month.

Whichever plan you pick, the investment range is the same and it is one of the widest in the UK market. You get UK, US and international shares, funds, over 1,000 exchange traded funds, investment trusts, and corporate and government bonds and gilts. If all you want is low cost ETF exposure, a specialist such as InvestEngine may cover your needs more cheaply.
ii also links to a standalone Cash Savings service provided by Flagstone, an FCA regulated savings platform. It needs a minimum deposit of £10,000, is not linked to your ii ISA, Personal Pension or Trading Account, and should not be confused with a Cash ISA. Savings rates and availability change, so check the live terms before applying.
If you would rather not choose investments yourself, ii offers a Managed ISA and Managed Portfolios for the pension, where its team selects and monitors a portfolio for you. Access is included in the same flat monthly subscription, but the portfolios are not free of percentage charges: ii lists ongoing charges of 0.13% to 0.21% a year, taken from your investments, depending on the portfolio. In a self-directed Stocks and Shares ISA you choose the investments yourself. When comparing ii with a managed provider such as Nutmeg, add these portfolio charges to the subscription.
ii’s family accounts are worth weighing separately from its headline fees. Plus lets up to five eligible family members invest up to £100,000 each without paying their own monthly subscription. Premium extends this to an unlimited number of eligible family members with up to £250,000 each, and they get Premium dealing and FX rates. Each family account stays individually owned, and eligibility and linking rules apply. For a couple or a family investing together, that can change the maths considerably. To see how ii’s flat fee compares with percentage based platforms at your portfolio size, our UK Broker Fees Calculator is quicker than doing the sums by hand.
On a percentage platform, doubling your portfolio doubles your bill. On ii it does not move. Over a couple of decades of compounding, that difference on a large portfolio can run into thousands of pounds.
UK, US and international shares, funds, over 1,000 ETFs, investment trusts, bonds and gilts. Whatever you want to hold, ii almost certainly offers it, and the range is identical on every plan.
Regular monthly investing costs nothing on any plan. Plus includes £3.99 of monthly trading credit and Premium £29.90, equivalent to one or ten UK or US share trades. The credit expires after 31 days and only helps if you place qualifying trades; it is not a deduction from the subscription.
ii's support team is UK based and reachable by phone. The company reports that more than half of its customers have stayed with it for over ten years, which is a reasonable signal on service quality.
Plus covers up to five family members with up to £100,000 each, and Premium covers unlimited eligible family members with up to £250,000 each, all without their own monthly fee. Junior ISAs for your children are included on both. For a household investing together this is unusually good value.
The £5.99 monthly minimum means £71.88 a year regardless of activity. On a £5,000 portfolio that is roughly 1.4% a year, which is far more than a percentage platform would charge you at that size.
To open a Junior ISA you need the Plus plan at £14.99 a month. Several rivals offer a Junior ISA at no platform charge at all, so ii is a poor choice if children's accounts are your main reason for joining.
Pass £100,000 and you move to Plus automatically, so your monthly cost jumps from £5.99 to £14.99. It is still competitive at that portfolio size, but the step up is worth planning for rather than discovering on your statement.
ii charges a flat monthly fee rather than a percentage of your portfolio. Core is £5.99 a month and is limited to portfolios up to £100,000. Plus is £14.99 a month with no portfolio limit. Premium is £39.99 a month, with lower dealing and FX rates, £29.90 of monthly trading credit and extras such as ii360.
Everyone starts on Core, and you move to Plus automatically once your portfolio passes £100,000. You can also move up voluntarily to unlock the Junior ISA or the family accounts. The fee is normally paid by Direct Debit, which is the only payment method available on the Core plan. A pension admin fee is included within the monthly cost rather than charged on top: £2.50 including VAT on Core, and £6 on Plus and Premium. ii publishes the full breakdown on its charges page.
| Fee or benefit | Core | Plus | Premium |
|---|---|---|---|
| Subscription a month | £5.99 | £14.99 | £39.99 |
| Subscription a year | £71.88 | £179.88 | £479.88 |
| Portfolio limit | Up to £100,000 | No limit | No limit |
| UK and US shares, ETFs and investment trusts, per trade | £3.99 | £3.99 | £2.99 |
| Fund trades | £3.99 | £1.49 | Free |
| Other international shares, per trade | £9.99 | £7.99 | £5.99 |
| Monthly trading credit | None | £3.99 (one trade) | £29.90 (ten trades) |
| Dividend reinvestment, per holding | £0.99 | £0.99 | Free |
| Foreign exchange | 0.75% | 0.75% on the first £50,000; 0.25% above | 0.25% |
| Family accounts | Not included | Up to 5; £100,000 each | Unlimited; £250,000 each |
| Junior ISA | No | Yes | Yes |
| ii360 access | +£20 a month | +£20 a month | Included; ii360 trades charged separately |
| Business Account | +£30 a month | +£30 a month | £30 charge waived, subject to eligibility |
Published online charges as checked on 23 October 2026. Monthly trading credit is valid for 31 days and cannot be rolled over. Other dealing, FX, tax, regulatory and administration charges may apply, and ii360 trades have a separate fee schedule. See ii's latest fees.
Trading is charged separately from your plan fee. On Core, funds and UK or US shares cost £3.99 per trade and other international shares are £9.99. On Plus, funds drop to £1.49, UK and US shares stay at £3.99 and international shares fall to £7.99. On Premium, fund trades are free, UK and US shares cost £2.99 and international shares are £5.99.
Regular monthly investing is free on every plan. Dividend reinvestment costs £0.99 per holding on Core and Plus, and is free on Premium. Plus includes £3.99 of monthly trading credit and Premium £29.90, equivalent to one or ten UK or US share trades. The credit expires after 31 days, cannot be carried over and is not a deduction from the subscription, so it only helps if you place qualifying trades. Trades placed in an ii360 account follow ii360’s own charges instead.
Foreign exchange is charged at 0.75% on Core. On Plus it is 0.75% on the first £50,000 and 0.25% above that, and on Premium it is a flat 0.25%. Telephone trades cost £49. Next day withdrawals in sterling or euros are free, while same day or other currency withdrawals cost £15.
There are no transfer charges in or out, including full in specie transfers where you keep the same investments. Some situational admin charges do apply, including £25 for a failed payment, £5 a month for non-UK residents and £35 plus VAT for a share certificate withdrawal. Government taxes are separate, including 0.5% UK stamp duty on share purchases and a £1.50 PTM levy on UK trades above £10,000.
A flat fee is not automatically cheaper. The examples below compare only the yearly platform or holding charge for a single account, using each provider's published rates, and leave out dealing, FX, fund charges and trading credit.
| Illustrative portfolio | Interactive Investor | Hargreaves Lansdown |
|---|---|---|
| £10,000 in funds | £71.88 (Core) | £35.00 |
| £50,000 in funds | £71.88 (Core) | £175.00 |
| £150,000 in ETFs in a Stocks and Shares ISA | £179.88 (Plus) | £150.00 (capped) |
ii's Core plan applies up to a £100,000 portfolio and Plus above it. Hargreaves Lansdown charges 0.35% a year on the first £250,000 in funds and caps its charge on shares and ETFs at £150 a year. The ETF example shows why there is no single balance at which ii becomes the cheaper option. Figures use ii's charges and HL's charges from 1 March 2026, checked on 23 October 2026, and are not guaranteed costs for every investor. Model your own portfolio with our UK Broker Fees Calculator, or see our Hargreaves Lansdown vs Interactive Investor comparison.
ii operates a UK based telephone helpdesk for account, trading and transfer queries. Telephone dealing is available but costs £49 per trade, so it is worth placing trades online where you can.
Logged in customers can raise queries by secure message, and ii runs a detailed online help centre covering fees, transfers, plan changes and tax questions.
A moderated customer forum included on every plan, where investors discuss holdings, platform questions and market views. It is a genuine differentiator against app-only platforms.
ii is a phone-answering platform rather than an app-only one, and its support team is based in the UK. The company points out that more than half of its customers have been with it for over ten years, which is a reasonable proxy for people being satisfied enough to stay put.
Support matters most at the awkward moments: a pension transfer that stalls, a corporate action you do not understand, or a bereavement. Being able to reach a person on the phone is worth something in those situations, and it is one of the reasons ii and Hargreaves Lansdown both retain customers who could pay less elsewhere.
ii also runs the ii Community, a moderated forum where customers discuss holdings and platform questions with each other. It is included on every plan and is a genuinely useful supplement to the official help centre.
The research side is strong. Every plan includes ii’s investment research and insight, its expert fund and trust selections, and shareholder voting rights on eligible holdings, which not all platforms pass through to customers.
Opening an ii account is done online and takes a few minutes. You will need your National Insurance number, your bank details and some basic personal information. There is no minimum deposit to open an account, though regular investing starts at £25 a month.
Every new customer joins on the Core plan at £5.99 a month. You will need to set up a Direct Debit for the monthly fee, as that is the only accepted payment method on Core. You can change plan later from inside your account, though you have to stay on a new plan for at least a month before dropping back to a cheaper one.
If you are moving from another provider, ii does not charge for transfers in and assigns a case handler to walk you through it. Transfers can still take several weeks depending on who you are leaving, and it is worth checking whether your current provider charges an exit fee first.
One point worth planning around: the Junior ISA is not available on the Core plan. If you are opening ii specifically for your children’s accounts, you will need Plus at £14.99 a month from the start, which changes the cost comparison against platforms like Hargreaves Lansdown that charge nothing at all on a Junior ISA.
Once you are set up, you can hold multiple currencies in the Trading Account and the Personal Pension, converting when the rate suits you rather than being forced to convert on every trade. That is a useful feature if you invest regularly in US shares.
Your services are provided by Interactive Investor Services Limited, which is authorised and regulated by the Financial Conduct Authority under firm reference number 141282. The company is registered in England with company number 02101863, and its registered office is at 201 Deansgate, Manchester.
Your investments are registered in the name of a separate company, Interactive Investor Nominee Services Limited, which keeps client assets ring fenced from ii’s own money. If ii were declared in default and there were a shortfall, eligible customers would be covered by the Financial Services Compensation Scheme up to £85,000 per claimant for investment claims.
Uninvested cash is treated differently. ii holds it in designated client accounts at UK banks, where eligible customers may be protected up to £120,000 per person, per bank, under the FSCS deposit rules, and that limit includes any money you hold with the same bank directly or through other providers. The protection that applies depends on your circumstances, and neither limit covers your investments falling in value.
ii is not independent. It was bought by the asset manager abrdn, now trading as Aberdeen, in 2022, and operates as part of that group. It says it looks after more than £100bn of investments for over 500,000 customers, and says it handles roughly one in every seven investments bought or sold by the UK public.
Being owned by a large listed asset manager is generally a stability signal, though it is worth being aware of the relationship if you are considering Aberdeen’s own funds on the platform.
ii’s flat fee can be compelling on larger portfolios, but it is not the right answer for everyone, and a £5.99 monthly minimum is a real cost on a small portfolio. We looked at total cost, beginner friendliness, product range, regulatory standing and user feedback to pick the alternatives below. You can also browse our full set of UK broker reviews.
Best commission-free alternative
eToro
No commission on real share and ETF dealing and no monthly platform fee, plus CopyTrader. Currency conversion and withdrawal fees apply, and there is no SIPP.
eToro is a multi-asset investment platform. The value of your investments may go up or down. Your capital is at risk. Sponsored link.

Best for beginners
InvestEngine
Commission-free ETF investing with no platform fee on its DIY option, plus managed portfolios, a gentler start than ii’s much larger menu.
Capital at risk.

Closest rival
Hargreaves Lansdown
More research and a free Junior ISA, but a percentage fee rather than a flat fee, so it usually costs more on larger portfolios.
Capital at risk.

Best for low-cost index funds
Vanguard
The asset manager behind many of the index funds UK investors already hold, and its own platform is a low-cost route into them, albeit with a narrower range.
Capital at risk.

For experienced investors
Interactive Brokers
Access to markets worldwide and professional-grade tools, better suited to confident, hands-on investors.
Capital at risk.
The honest summary is that ii’s competitors often win on cost at smaller portfolio sizes, while ii’s flat fee becomes more attractive as a portfolio grows, especially one built from funds. If you are not sure where you fall, our Find My Broker tool and our AJ Bell review are useful next steps.
Yes. Your services are provided by Interactive Investor Services Limited, which is authorised and regulated by the Financial Conduct Authority under firm reference number 141282. Your investments are registered to a separate nominee company, keeping them ring fenced from ii's own money, and eligible customers are covered by the Financial Services Compensation Scheme up to £85,000 per claimant for investment claims. Uninvested cash held in client accounts at UK banks may be protected up to £120,000 per person, per bank. The FSCS does not protect you against your investments falling in value.
ii charges a flat monthly fee rather than a percentage. Core is £5.99 a month for portfolios up to £100,000, Plus is £14.99 with no limit, and Premium is £39.99. Trading is charged separately: on Core, funds and UK or US shares are £3.99 a trade. Regular monthly investing is free on every plan.
Core costs £5.99 a month and has a £100,000 portfolio limit. Plus costs £14.99 with no limit, and adds Junior ISAs, up to five family accounts with £100,000 each, cheaper fund dealing and £3.99 of monthly trading credit. Premium costs £39.99 and adds £29.90 of monthly trading credit, equivalent to ten UK or US share trades, lower dealing and FX rates, unlimited family accounts with £250,000 each and ii360 access. Premium's free trades do not apply to orders placed in an ii360 account.
It can be, if you regularly use the trading credit or benefit from the family accounts, ii360 or Business Account features. Premium still costs £479.88 a year before any other charges, and unused trading credit expires after 31 days. If you rarely trade and do not need the extra services, Plus or Core may offer better value, depending on your portfolio size.
Yes. Access to the Managed ISA is included in the flat monthly subscription, but ii lists ongoing portfolio charges of 0.13% to 0.21% a year, taken from your investments, depending on the portfolio. Your total cost can therefore be more than the subscription alone. Check the factsheet for the portfolio you choose.
It depends far more on your portfolio size than your experience level. The platform itself is straightforward and the Managed ISA removes the need to pick investments. But the £5.99 monthly minimum is a heavy drag on a small pot, so a beginner starting with a few thousand pounds will usually pay less on a commission free platform and can move to ii later.
Every plan includes a Trading Account, a Stocks and Shares ISA, a Managed ISA, a Personal Pension and the Managed Portfolios range. The Junior ISA is available only on the Plus and Premium plans. There is also a Joint Trading Account, charged separately at £14.99 a month. A standalone Cash Savings service provided by Flagstone is available too, but it is separate from these accounts and is not a Cash ISA.
It depends on how much you hold and what you hold. HL charges 0.35% a year on funds, so a £10,000 fund portfolio costs about £35 against ii's £71.88 on Core, while £120,000 in funds costs about £420 at HL against £179.88 on ii's Plus plan, which applies once your portfolio passes £100,000. For shares and ETFs, HL caps its charge at £150 a year, so a large ETF portfolio can cost less at HL than on ii Plus. These are platform charges only, before dealing, FX and fund costs.
No. ii does not charge for transfers in or out, including full in specie transfers where you keep the same investments. Next day withdrawals in sterling or euros are also free, though same day withdrawals cost £15. Check whether your existing provider charges an exit fee before you move.
Yes, but not on the entry level Core plan. Junior ISAs require the Plus plan at £14.99 a month, which then covers Junior ISAs for all of your children at no additional cost. If children's accounts are your only reason for joining, compare that against providers who charge nothing for a Junior ISA.
Your investments are held in a separate nominee company and are not ii's assets, so they should not be used to pay its creditors. If ii were declared in default and there were a shortfall, the Financial Services Compensation Scheme covers eligible investment claims up to £85,000 per person. Cash held in ii's client accounts at UK banks falls under separate deposit protection of up to £120,000 per person, per bank. ii is also part of the Aberdeen group, formerly abrdn, which acquired it in 2022.
Interactive Investor is the strongest flat fee option in the UK, and for the right investor it is a straightforwardly good deal. If you hold a decent sized portfolio, want an ISA and a pension in one place, and value being able to phone someone, ii can be difficult to beat on cost. The investment range is broad, the research is included, and the family accounts on Plus and Premium are unusually generous.
The catch is that the flat fee cuts both ways. At £5.99 a month you are paying £71.88 a year before you buy anything, which on a £5,000 portfolio is about 1.4%. The Junior ISA sitting behind the £14.99 Plus plan is another awkward gap. There is no universal balance at which ii becomes the cheapest option: an ETF-only ISA can produce a different result from a fund portfolio, and the move from Core to Plus above £100,000 changes the calculation again. Compare the subscription, what you hold, how often you trade and any ongoing investment charges. If your pot is small, look at eToro or another commission free option first.
vs
Hargreaves Lansdown vs Interactive Investor
A percentage fee against a flat monthly fee: Hargreaves Lansdown is usually cheaper on smaller fund portfolios, while ii's flat fee wins as your balance grows.
Read the full comparison →
vs
Interactive Brokers vs Interactive Investor
Two unrelated firms with similar names: Interactive Brokers wins on dealing and currency costs, while ii offers a flat fee, a direct SIPP and UK phone support.
Read the full comparison →
This review follows the same process we apply to every broker, so you can see what the verdict above is actually based on.

Bank Rate Rise 2026: What 4% Means For Savers And Investors
The Bank of England raised Bank Rate from 3.75% to 4% on 5 November 2026, the first increase since August 2023. Here is what the decision actually reaches…
Nvidia CEO Shock Exit: How Does This Affect UK Investors?
Jensen Huang, who co-founded Nvidia in 1993 and ran it for 33 years, resigned as president and chief executive on Thursday 12 November 2026, with immediate effect. The…
Inherited Pension Tax 2027: What Changes For Your Family
The two year rule that could turn a tax free inherited pension into taxable income ended on 28 October 2026. From 6 April 2027, most unused pension funds…
About YWM
For general information only, not financial advice. Investing puts your capital at risk.
The information provided on this page and throughout the website is for general information purposes only and does not constitute financial advice. It is important that you conduct your own research and consider your own personal circumstances before making any investment decisions.
While we strive to provide accurate product information at the time of publication, the information may be subject to change by the provider at any time. Please always verify the product information before making any decisions. Past results do not guarantee future profits.
If you use some of the links on Your Wallet Manager, we may receive a small fee from our partners, supporting the website's free usage. However, please be assured that our editorial content is never influenced by these links. We include them to help us keep the lights on and to support our mission of helping people make informed financial decisions regarding their wallet’s most important spendings.
Thank you for your understanding and support!
Our top picks
All reviews
Reviews hubHead-to-head comparisons
Fees, account types and features side by side.
Welcome offers
Best providers
Free tools
Categories
Knowledge hubAdding {{itemName}} to cart
Added {{itemName}} to cart