Skip links

Vanguard UK Review 2026

Stocks and Shares ISA, Personal Pension, Junior ISA and General Account

Vanguard logo

Capital at risk.

Our verdict

Vanguard is a simple, low-cost home for Vanguard's own index funds, and it is at its best once you have £32,000 or more invested. Below that, the flat £4 a month fee takes a bigger share of a small pot, and you can only ever hold Vanguard funds and ETFs.

A good fit if you

  • want a ready-made fund such as LifeStrategy and to leave it alone
  • have roughly £32,000 to £250,000 invested, where the fee is 0.15% a year
  • are saving for a child: the Junior ISA is 0.15% with no £4 minimum

Look elsewhere if you

  • are starting with a few hundred pounds, or less than £100 a month
  • want individual shares, investment trusts or other managers' funds
  • want a Lifetime ISA, a cash ISA or a joint account

Vanguard at a glance

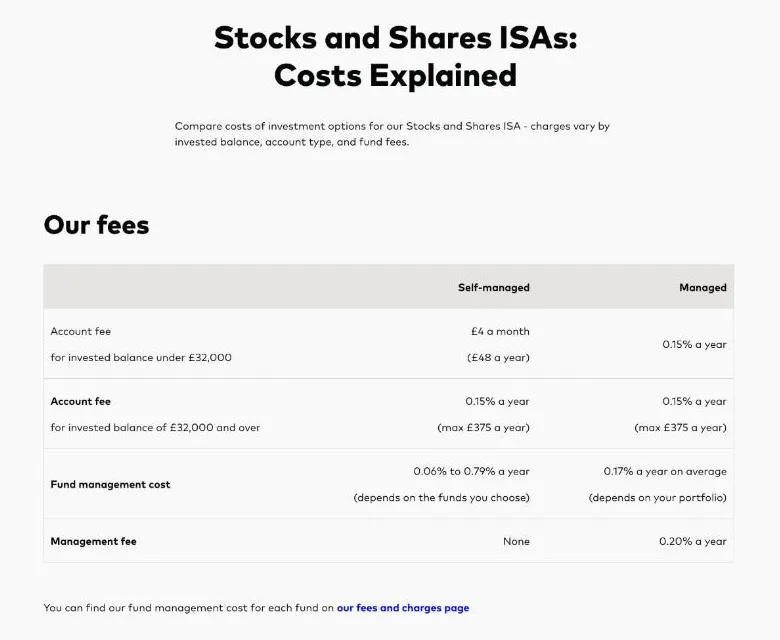
Account fee£4 a month below £32,000 invested; 0.15% a year from £32,000, capped at £375
Fund costs0.06% to 0.79% a year, depending on the fund
DealingNo charge on funds. ETFs free through twice-daily bulk dealing, or £7.50 a trade for a live price
AccountsStocks and Shares ISA, Junior ISA, Personal Pension (SIPP), General Account, plus a Managed ISA and Managed Pension
What you can buyMore than 85 Vanguard funds and ETFs only
Minimum to start£500 a fund, or £100 a month a fund. No minimum on an ISA transfer
Interest on cash1.95% a year (from 5 November 2026)
Exit and transfer feesNone
RegulationVanguard Asset Management Limited, authorised and regulated by the FCA. FSCS cover on investments up to £85,000
Phone support0800 587 0460, Monday to Friday, 9am to 5pm

Source: Vanguard fees and charges, Key Features documents (November 2025) and help centre, read 11 November 2026.

Who is Vanguard?

Vanguard is one of the world’s largest fund managers and says it has 50 million investors worldwide. In the UK, its platform for personal investors is run by Vanguard Asset Management Limited, which is authorised and regulated by the Financial Conduct Authority.

The platform does one thing: it lets you buy Vanguard’s own funds and ETFs inside an ISA, a pension, a Junior ISA or a General Account. You can pick the funds yourself, or pay a little more for Vanguard to build and manage a portfolio for you.

It is an online service. Vanguard says it is not the right fit if you want to deal by phone, receive paper statements, take no investment risk or get financial advice.

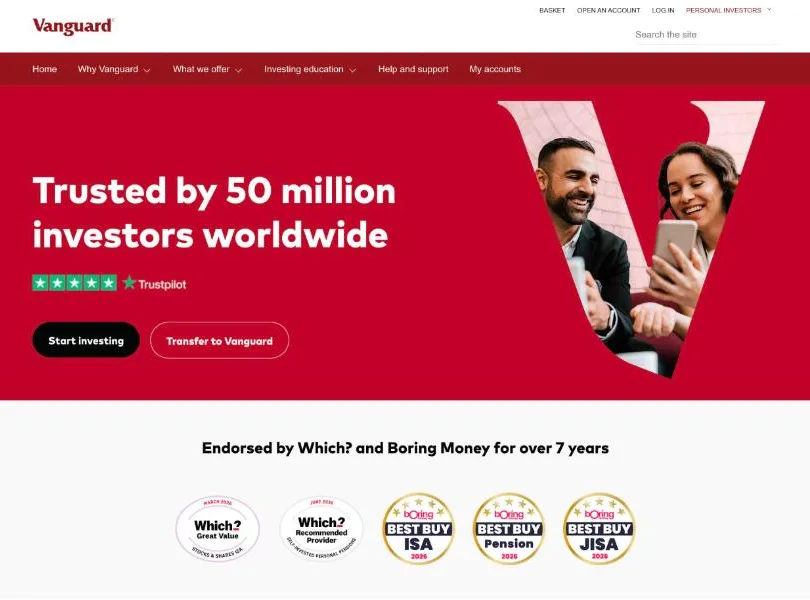
Vanguard UK Investor home page

Vanguard's accounts

Stocks and Shares ISA

Invest up to £20,000 a year with no tax on income or gains. Vanguard’s ISA is flexible, so money you take out can be paid back in during the same tax year without using more of your allowance. You start with £500 a fund or £100 a month a fund, and there is no minimum if you transfer an ISA in from another provider.

Vanguard Stocks and Shares ISA fees: self-managed and managed

Junior ISA

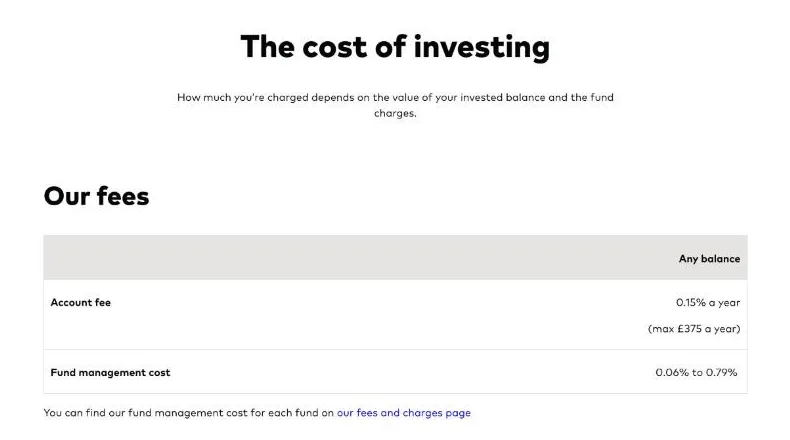
For children under 18, with up to £9,000 a year going in. A parent or legal guardian opens it, but anyone can pay in. It costs 0.15% a year on any balance, with no £4 minimum, so £10,000 costs £15 a year in account fees. The money belongs to the child at 18. Unlike the adult ISA, Vanguard’s Junior ISA is not flexible.

Vanguard Junior ISA fees: 0.15% account fee on any balance

Personal Pension (SIPP)

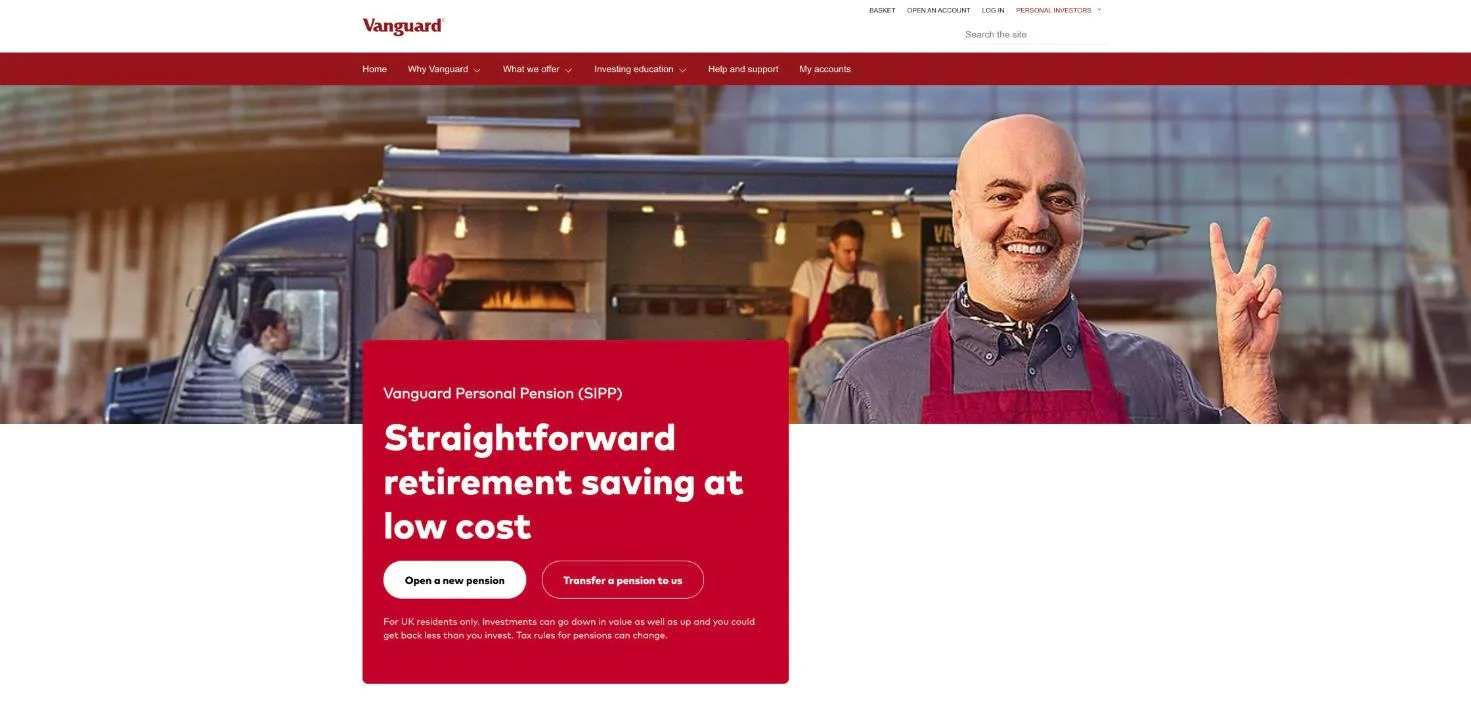
A self-invested personal pension, with tax relief on what you pay in. You can take money out from age 55, rising to 57 from 2028. It carries the same account fee as the ISA, and its value counts towards your £32,000 total.

Vanguard Personal Pension (SIPP) page

General Account

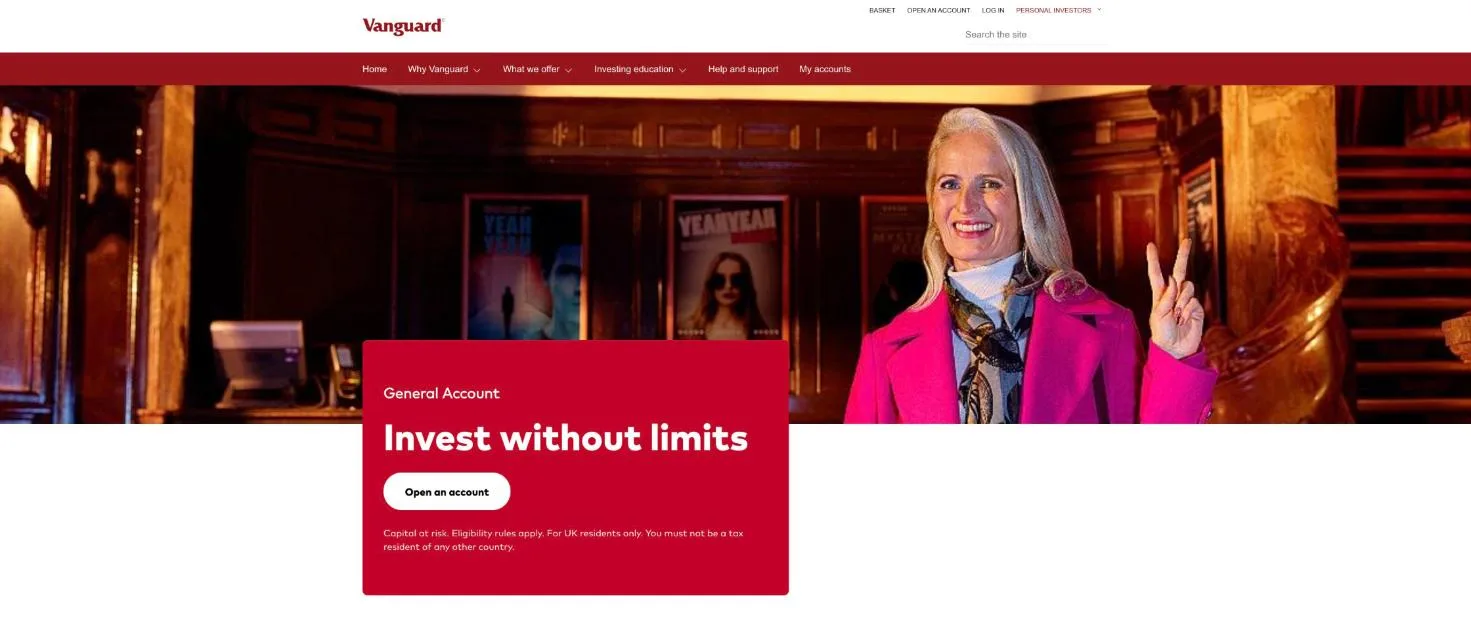
An ordinary investment account for money beyond your ISA allowance. There is no limit on what you pay in, but income and gains outside an ISA or pension can be taxed.

Vanguard General Account page

Managed ISA and Managed Pension

If you would rather not choose funds, Vanguard picks and rebalances a portfolio for you based on how much risk you are comfortable with. This is a managed service, not financial advice.

Yearly costManaged ISAManaged Pension
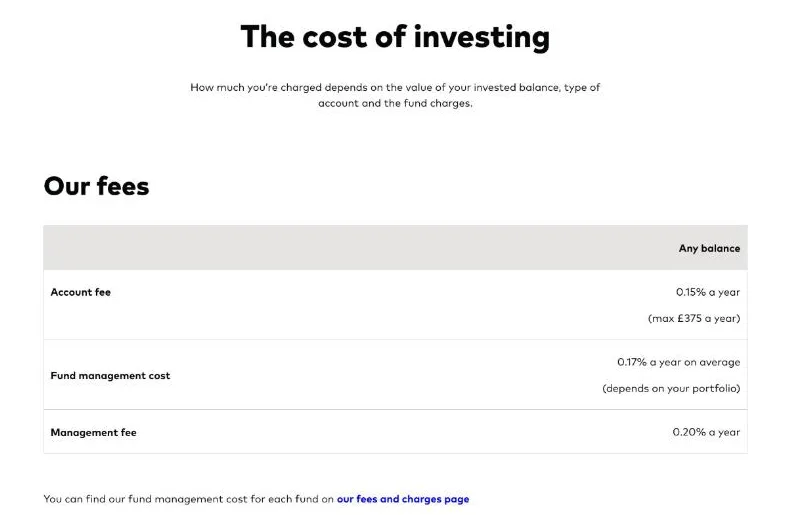
Account fee0.15% (max £375)0.15% (max £375)
Management fee0.20%0.30%
Fund costs (average)0.17%0.17%
On £10,000 (Vanguard's example)£52 a year£62 a year

If a managed account is the only one you hold, the £4 minimum does not apply. Open a self-managed account alongside it and the minimum covers both.

Vanguard Managed ISA fees: account fee, fund costs and 0.20% management fee

What you can invest in

You can choose from more than 85 Vanguard funds and ETFs, and nothing else: there are no individual shares, investment trusts or funds from other managers. For most people building a long-term portfolio, a handful of these funds is enough. The most popular choices are:

LifeStrategy

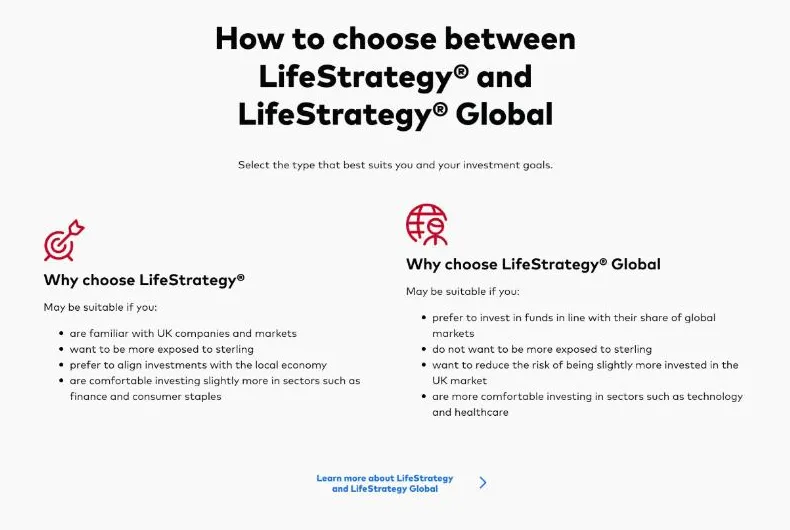
Ready-made mixes of shares and bonds, from 20% to 100% in shares. Ongoing cost 0.20%, cut from 0.22% in January 2026. By the end of June 2026 Vanguard had reduced the UK share of these funds to around 20% of the shares and bonds, from around 25% and 35%.

LifeStrategy Global

Launched on 22 January 2026 with the same idea, but invested in line with world markets, so only about 3% of the shares are in the UK. Ongoing cost 0.20%.

Target Retirement

Pick the fund for the year you expect to retire. It moves gradually from shares into bonds as that date gets closer. Ongoing cost 0.24%.

Single index funds and ETFs

One fund for one market, such as FTSE Global All Cap (0.23%), which holds shares across the world. A few specialist funds cost more, for example Global Emerging Markets at 0.78%.

Sources: Vanguard self-managed costs and charges (20 August 2026); Vanguard fund changes; read 11 November 2026.

Vanguard page comparing LifeStrategy and LifeStrategy Global funds

Invest in around 85 Vanguard index funds and ETFs, with account fees capped at £375 a year.

Capital at risk.

Capital at risk.

How much does Vanguard cost?

You pay two things: Vanguard’s account fee, and the running cost of each fund you hold. There is no dealing charge on funds and no fee to leave.

The account fee

Vanguard adds up everything you have invested across your ISA, Personal Pension and General Account. Cash and any Junior ISA are left out.

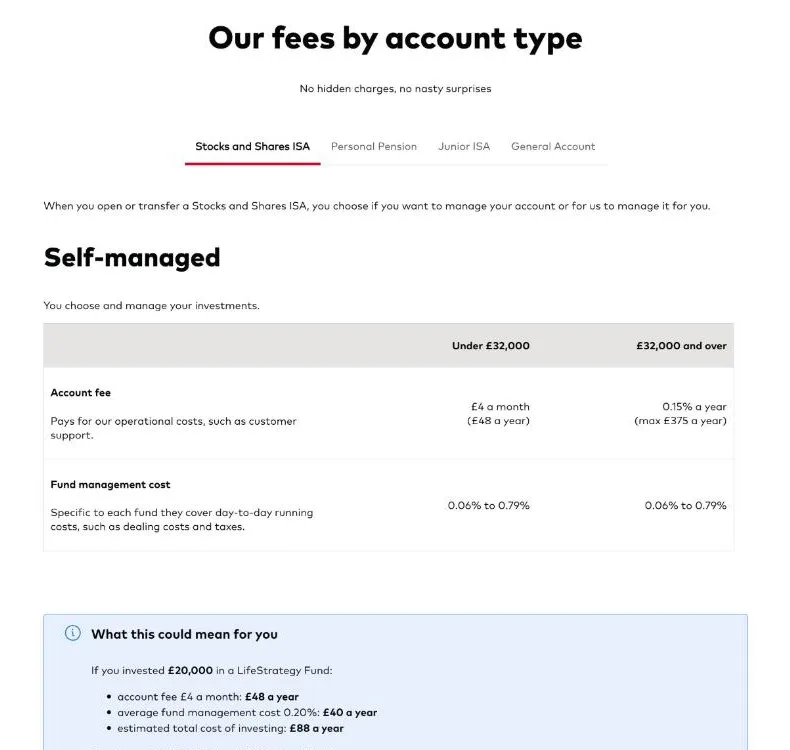
  • Under £32,000: £4 a month, which is £48 a year
  • £32,000 and over: 0.15% a year, capped at £375

The two meet exactly at £32,000, where 0.15% also comes to £48, so your cost does not jump as you cross the line. The £375 cap is reached at £250,000. The fee is taken every three months, by Direct Debit or from cash in your account. If there is not enough cash, Vanguard sells units, starting with your largest fund.

Vanguard fees by account type, showing the £4 a month and 0.15% account fee tiers

What you would pay in a year

Amount investedAccount feeFund cost at 0.20%Total a yearAs a share of your pot
£1,000£48£2£505.00%
£5,000£48£10£581.16%
£20,000£48£40£880.44%
£32,000£48£64£1120.35%
£50,000£75£100£1750.35%
£100,000£150£200£3500.35%
£250,000£375£500£8750.35%
£500,000£375£1,000£1,3750.28%

YourWalletManager calculation from Vanguard's published rates. Self-managed accounts, balance held for the whole year, no Quote and deal trades. Fund cost at 0.20%, the ongoing cost of a LifeStrategy fund; your funds may cost more or less. Use our broker fees calculator to compare platforms.

Fund costs

Each fund has its own running cost, which Vanguard puts at 0.06% to 0.79% a year. It is taken inside the fund’s price, so you will not see it as a separate charge on your statement. LifeStrategy funds cost 0.20% and Target Retirement funds 0.24%.

Buying and selling ETFs

Ordinary funds are priced once each working day, and you buy or sell at the next price. ETFs trade on the London Stock Exchange throughout the day, and Vanguard gives you two ways to deal:

  • Bulk dealing, free: your order is grouped with other investors’ and placed at 10:15 or 14:10
  • Quote and deal, £7.50 a trade: a live price while the market is open, 8am to 4.30pm

ETFs also carry a small spread cost of 0.01% to 0.26%. The Vanguard app does not offer live ETF trading yet.

Interest on cash

Money waiting to be invested earns 1.95% a year (from 5 November 2026), paid on the first working day of each month. Vanguard keeps any interest it earns above that rate. Cash is not counted for the account fee.

What is free

There is no charge to switch funds, withdraw money, transfer out or close your account. If you ask for a payment by CHAPS, Vanguard charges £25.

Sources: Vanguard fees explained; self-managed costs and charges (20 August 2026); Key Features of the ISA, Junior ISA and General Account (November 2025); Vanguard help centre pages on dealing times, the minimum account fee and interest on cash; read 11 November 2026.

Platform, app and support

Most of what you do happens on Vanguard’s website: opening accounts, choosing funds and managing payments. You can only open an account there, not in the app.

The Vanguard app

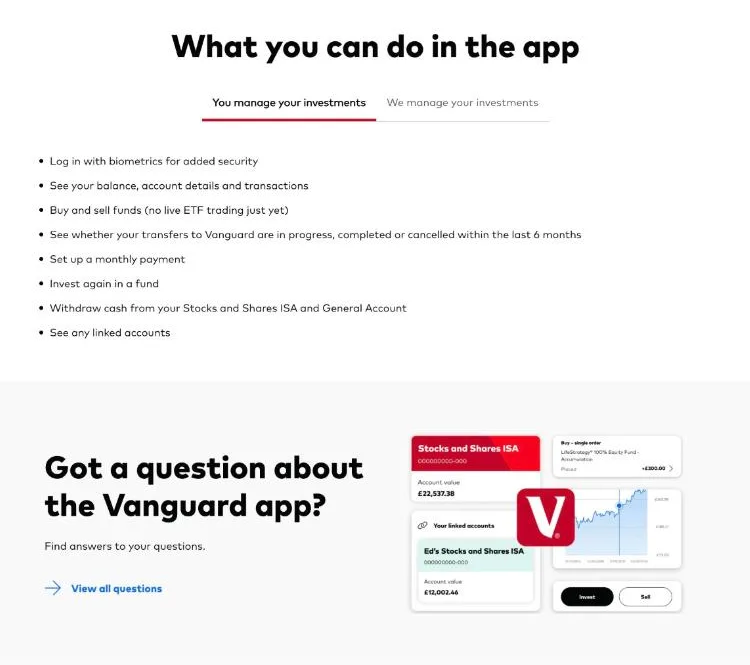
The app, for iPhone and Android, lets you:

  • log in with your fingerprint or face
  • see your balances, account details and transactions
  • buy and sell funds, and set up monthly payments
  • withdraw cash from your ISA and General Account
  • check whether a transfer to Vanguard has gone through

It does not offer live ETF trading yet and is not designed for tablets. Vanguard itself describes the app as a work in progress, so it suits checking in rather than managing everything.

Vanguard app page listing what you can do in the app

Help choosing a fund

New clients can use Vanguard’s targeted support. You answer a few questions about your goals and how you feel about risk, and Vanguard suggests a fund. Everyone with similar answers gets the same suggestion, so it is a step short of personal advice, and you do not have to follow it.

Customer support

  • Phone: 0800 587 0460, or +44 (0)20 3753 5087 from abroad, Monday to Friday, 9am to 5pm, closed on public holidays
  • Secure message from your online account
  • Email: personalinvestors@vanguard.co.uk (Vanguard asks you not to include account details)
  • A chatbot on Vanguard’s website for quick questions

There is no phone dealing: buying and selling happens online.

Vanguard contact details: secure message and phone lines, Monday to Friday 9am to 5pm

Opening an account

  1. Choose an account on Vanguard’s website: Stocks and Shares ISA, Junior ISA, Personal Pension or General Account.
  2. Enter your details, including your National Insurance number and UK bank account.
  3. Pick your funds, or use targeted support for a suggestion.
  4. Pay in £500 a fund, set up £100 a month a fund, or transfer an existing ISA or pension.

You need a UK bank account. Vanguard does not accept US persons, joint accounts or companies.

Start a Vanguard ISA, Junior ISA or Personal Pension from £100 a month.

Capital at risk.

Capital at risk.

Is Vanguard safe?

Vanguard Asset Management Limited is authorised and regulated by the Financial Conduct Authority. Your investments are held separately from Vanguard’s own money under FCA client asset rules. If the firm failed and could not return your assets, the Financial Services Compensation Scheme covers eligible investments up to £85,000 per person.

Two things are worth knowing. The FSCS does not protect you against your investments falling in value, which is the risk you take when you invest. And the higher £120,000 limit that came into force on 1 December 2025 applies to cash deposits with banks and building societies, not to investment claims.

Pros and cons

Pros

  • Low cost from £32,000: 0.15% a year, capped at £375
  • No dealing charge on funds, and free ETF bulk dealing twice a day
  • Ready-made funds such as LifeStrategy keep investing simple
  • Junior ISA at 0.15% with no monthly minimum
  • No fees to switch, withdraw or transfer out

Cons

  • The £4 a month minimum is 0.96% a year on £5,000, before fund costs
  • Only Vanguard funds and ETFs: no shares or investment trusts
  • Higher entry point: £500 or £100 a month for each fund
  • No Lifetime ISA, cash ISA or joint accounts
  • Basic app with no live ETF trading

Sources: Vanguard app page, targeted support, Supporting your needs, target market and Client Terms (August 2026); read 11 November 2026.

Vanguard alternatives worth considering

Vanguard is one of the cheapest ways to hold Vanguard’s own funds, but its range stops there. If you want individual shares, other fund managers, research or a fully managed service, these are the alternatives we would look at first.

Best for shares as well as funds

Trading 212

Commission-free shares and ETFs, including many Vanguard ETFs, with no platform fee and a flexible ISA.

Visit broker →

Capital at risk.

Best for low-cost ETF portfolios

InvestEngine

No platform fee on DIY ETF portfolios built from providers including Vanguard, with managed portfolios if you want help.

Visit broker →

Capital at risk.

Closest like-for-like alternative

AJ Bell

ISA, SIPP, Lifetime ISA and Junior ISA with a much wider choice of funds and shares, at a low percentage fee.

Visit broker →

Capital at risk.

Best for funds and research

Hargreaves Lansdown

A wide range of funds, shares and bonds, plus in-depth research and phone support.

Visit broker →

Capital at risk.

Best if you want it managed for you

J.P. Morgan Personal Investing (Nutmeg)

Fully managed portfolios from £500, with a 14-year published track record across ten risk levels.

Visit broker →

Capital at risk.

The information provided on this page and throughout the website is for general information purposes only and does not constitute financial advice. It is important that you conduct your own research and consider your own personal circumstances before making any investment decisions.

Every platform here is authorised by the FCA. For head-to-heads, see Trading 212 vs Vanguard and AJ Bell vs Vanguard, or answer a few questions in our Find My Broker quiz.

Frequently Asked Questions

Yes. Vanguard Asset Management Limited is authorised and regulated by the Financial Conduct Authority, and it is part of one of the largest asset managers in the world. Client assets are held separately from the company's own money under FCA client asset rules, and eligible investments are covered by the Financial Services Compensation Scheme up to £85,000 per person if the firm were to fail. The FSCS does not protect you against your investments falling in value.

Vanguard charges one account fee across all your accounts. Below £32,000 invested it is £4 a month, which is £48 a year. At £32,000 and above it is 0.15% a year, capped at £375, and that cap is reached at £250,000. On top of the account fee, each fund carries its own ongoing charge of roughly 0.06% to 0.79%. There is no dealing commission on Vanguard funds.

£500 as a lump sum or £100 a month, for each fund you choose. The same minimums apply to the ISA, Junior ISA, Personal Pension and General Account, and there is no minimum if you transfer an ISA in. Several UK platforms let you start with much less.

No. Vanguard Investor offers only Vanguard's own funds and exchange traded funds, around 85 of them, and there are no individual shares, investment trusts or third party funds. If you want to hold individual companies alongside index funds you would need a different platform, or a second account elsewhere.

No. Vanguard offers a stocks and shares ISA, a Junior ISA, a Personal Pension and a General Account, plus the Managed ISA service. There is no Lifetime ISA and no cash ISA, so anyone saving for a first home through a LISA will need a second provider.

It depends on how much you are starting with. The platform itself is about as simple as UK investing gets, and the LifeStrategy range removes most of the decisions. The catch is cost at the bottom end: the £4 monthly minimum is the equivalent of 4.8% a year on £1,000, and the £500 lump sum or £100 monthly entry point rules out starting very small. Beginners with a few hundred pounds will usually do better elsewhere.

No. There is no charge to transfer out, switch funds, withdraw money or close your account. In specie transfers, meaning moving your funds without selling them, are possible where the receiving provider supports them.

It depends on how much you have. Below £32,000 you pay a flat £48 a year, which is 0.96% on £5,000 but 0.24% on £20,000. From £32,000 to £250,000 you pay 0.15%, and above that the £375 cap makes it cheaper still as a share of your pot. Platforms with no account fee can work out cheaper on small pots, and platforms that cap their fee on ETFs and shares can be cheaper for large ETF portfolios. Our broker fees calculator shows where you fall, and our platform comparisons go platform by platform.

Yes. Cash waiting to be invested earns 1.95% a year (from 5 November 2026), paid monthly. Vanguard keeps any interest it earns above that rate, and the account fee is not charged on cash.

Yes, through the Managed ISA and Managed Pension. Both have the 0.15% account fee and average fund costs of 0.17%, plus a management fee of 0.20% on the ISA or 0.30% on the pension. Vanguard chooses and rebalances the funds based on your attitude to risk. It is not financial advice.

Conclusion: is Vanguard worth it?

Vanguard does one job well. If you want to put money into a few low-cost index funds and leave it there, few platforms make it simpler, and between £32,000 and £250,000 its 0.15% fee with no dealing charges is competitive. The Junior ISA is cheap at any size.

The weak points are at the edges. On a small pot the £48 a year minimum takes a big bite, and if you want shares, investment trusts or another manager’s funds, Vanguard cannot help. If you are starting with a few hundred pounds, you will usually pay less on a platform with no monthly minimum: see the alternatives above, or run your numbers through our broker fees calculator.

How does Vanguard compare?

Other recommended brokers

How we review brokers

This review follows the same process we apply to every broker, so you can see what the verdict above is actually based on.

  • What we assessCost, safety and regulation, investment range, platform experience, account options, and support.
  • Where it comes fromFee schedules, key features documents, terms and conditions, and the FCA Register.
  • How often we checkAt least quarterly, and sooner when a broker changes its charges or accounts.
  • IndependenceCommercial relationships do not change our verdict, or what we write about a broker.
Every broker we review is authorised by the Financial Conduct Authority.Our review methodology

Don't forget to visit our Knowledge Hub for more useful information on all things personal finance